
Free Credit Counselling Canada: Services by Province (2026 Guide)
October 28, 2025
Free Credit Counselling Canada: Get Help Before Your Debt Gets Worse
Last Updated: July 2026
If you’re struggling with debt, you’re not alone. Rising living costs, higher interest rates and increasing household expenses have left many Canadians searching for free credit counselling to help them regain control of their finances.
The good news is that many non-profit credit counselling agencies across Canada offer free initial consultations. During these sessions, a certified credit counsellor can review your financial situation, explain your debt relief options and help you create a realistic plan to manage your debt.
Depending on your circumstances, they may recommend budgeting support, a Debt Management Plan (DMP), debt consolidation or refer you to another debt solution where appropriate. Their goal is to help you understand your options so you can make an informed decision before your financial situation becomes more difficult.
This guide explains how free credit counselling works in Canada, what services are available in each province, what you can expect during your first appointment and how to choose a reputable non-profit organization.

What Is Free Credit Counselling in Canada?
Free credit counselling in Canada is professional financial guidance designed to help individuals understand their debts, create a realistic budget and explore suitable repayment options.
Certified credit counsellors assist by:
- Reviewing your full financial situation
- Creating a realistic monthly budget
- Providing financial education and credit coaching
- Negotiating lower interest rates with creditors
- Helping you enter a structured repayment program
Unlike bankruptcy or consumer proposals, credit counselling focuses on education, empowerment, and long-term financial improvement.
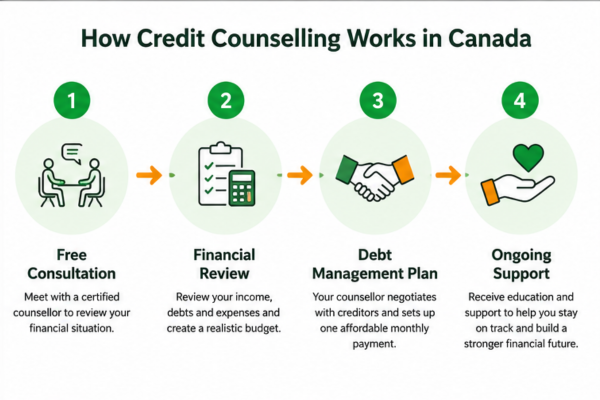
How Credit Counselling Works in Canada
Here’s what you can expect:
1. Free Initial Consultation
Meet online or in person with a certified counsellor to assess your income, debts, expenses, and financial challenges.
2. Financial Review & Budget Support
The counsellor helps you design a realistic spending plan and understand your options – including consolidation loans, repayment plans, or alternative solutions.
3. Debt Management Plan (DMP)
If appropriate, the counsellor can negotiate with your creditors to lower or eliminate interest and combine debts into one affordable monthly payment.
4. Education & Ongoing Support
You’ll receive guidance on rebuilding credit, reducing reliance on borrowing, and maintaining long-term financial health.
Many of Canada’s largest credit counselling agencies operate as non-profit organizations – meaning their goal is to help, not profit from your debt.
Free Credit Counselling Services by Province
Many Canadians search for free credit counselling because they want independent advice before choosing a debt solution. While services vary slightly between organizations, most provinces have access to accredited non-profit credit counselling agencies that provide free initial consultations and financial education.
Most provinces are served by established non-profit organizations that provide free financial assessments, budgeting advice, debt management support and educational resources. Some agencies also offer telephone and virtual appointments for Canadians living in remote communities.
Ontario
- Free financial assessments
- Budget planning
- Debt Management Plans
- Credit education
British Columbia
- Free debt counselling
- Budget assistance
- Debt repayment planning
- Credit rebuilding guidance
Alberta
- Free consultations
- Debt management advice
- Financial coaching
- Budget support
Saskatchewan
Residents can access non-profit credit counselling services offering budgeting assistance, debt advice and financial education.
Manitoba
Free consultations are available through several accredited organizations that specialise in debt management and financial education.
Quebec
Many agencies offer both English and French-language counselling services together with budgeting assistance and debt management guidance.
New Brunswick
Residents of New Brunswick can access non-profit credit counselling services that provide free financial assessments, budgeting advice and debt management support.
Nova Scotia
Several non-profit organizations offer free credit counselling, financial education and Debt Management Plans for eligible residents of Nova Scotia.
Prince Edward Island
Residents of Prince Edward Island can access free initial credit counselling consultations, budgeting assistance and debt repayment guidance.
Newfoundland and Labrador
Non-profit credit counselling agencies serving Newfoundland and Labrador offer free financial assessments, budgeting support and debt management advice.
Yukon
Residents of Yukon can usually access free credit counselling through telephone or virtual appointments provided by accredited non-profit organizations.
Northwest Territories
Free credit counselling services are available through organizations offering remote financial counselling, budgeting assistance and debt management support.
Nunavut
Where local offices are unavailable, residents of Nunavut can access free credit counselling through virtual or telephone appointments with accredited non-profit agencies.
Before booking an appointment, confirm that the agency is a registered non-profit organization, review any fees that may apply if you enrol in a Debt Management Plan and verify that its counsellors hold recognised professional credentials.
Is Credit Counselling Really Free?
In many cases, yes. Most non-profit credit counselling agencies in Canada provide a free initial consultation. During this appointment, a certified counsellor reviews your income, debts, monthly expenses and financial goals before explaining the available debt relief options.
If you decide to enrol in a Debt Management Plan (DMP), the organization may charge a modest administration fee. Any fees should be explained clearly before you agree to participate, allowing you to make an informed decision.
Fees vary between agencies and may include a set-up fee, monthly administration fee or other service charges. Ask for a complete written breakdown of the costs before agreeing to a Debt Management Plan.
Top Benefits of Credit Counselling Canada
| Benefit | Why It Matters |
|---|---|
| Lower Interest Rates | Counsellors can often negotiate reduced or zero interest on unsecured debts. |
| Simplified Payments | Combine multiple payments into one easy monthly plan. |
| Avoid Bankruptcy | May provide an alternative to formal insolvency where a Debt Management Plan is affordable and accepted by participating creditors. |
| Professional Guidance | Get advice from certified financial experts. |
| Structured Debt Repayment | A Debt Management Plan can provide a defined repayment schedule and help you repay participating unsecured debts in full. |
| Financial Education | Learn budgeting, credit use, and money management skills that last a lifetime. |
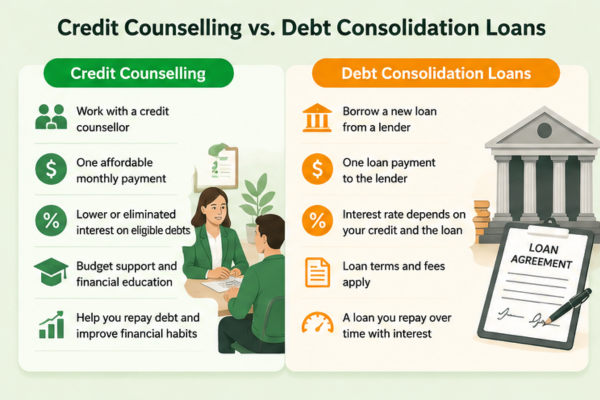
Credit Counselling vs. Debt Consolidation Loans
Both options can simplify debt repayment, but they work differently.
| Feature | Credit Counselling and a DMP | Debt Consolidation Loan |
|---|---|---|
| How It Works | A credit counsellor may arrange one monthly payment and ask participating creditors to reduce or waive interest. | You take out a new loan and use it to repay selected existing debts. |
| Debt Repaid | You generally repay the participating debts in full, along with any applicable agency fees. | You repay the new consolidation loan, including interest and fees. |
| Approval | Creditors must agree to participate in the Debt Management Plan. | You must meet the lender’s credit, income and affordability requirements. |
| Credit Impact | The plan and included accounts may be reflected on your credit report. | The application and new account may affect your credit report and score. |
| Best Suited To | People who need budgeting support and a structured plan for eligible unsecured debts. | Borrowers who qualify for a loan with manageable repayments and worthwhile overall costs. |
Who Should Consider Credit Counselling?
Credit counselling may be right for you if you:
✅ Struggle to make minimum payments
✅ Carry multiple high-interest credit cards
✅ Receive collection calls or past-due notices
✅ Want to avoid bankruptcy or consumer proposals
✅ Need guidance building a sustainable budget
✅ Feel overwhelmed and unsure where to start
Even if debt isn’t severe yet, early counselling can prevent larger financial issues later.
What Should You Bring to Your First Credit Counselling Appointment?
Preparing your financial information in advance allows the counsellor to provide more accurate guidance.
- Proof of income
- Monthly household expenses
- Credit card statements
- Loan statements
- Collection notices (if applicable)
- A list of your regular monthly payments
- Questions you would like answered
Having this information available allows the counsellor to assess your financial position and discuss the most suitable options for your circumstances.
Credit Counselling and Your Credit Report
Speaking with a credit counsellor does not by itself affect your credit score. However, enrolling in a Debt Management Plan may affect how participating accounts are reported by the credit bureaus.
- Accounts included in the plan may be identified as being repaid through a special arrangement.
- Access to new credit may be more limited while the plan is active.
- Missed payments before or during the plan may continue to affect your credit history.
- Completing the plan shows that participating debts were repaid according to the agreed arrangement.
Before enrolling, ask the agency how the plan may be reported to Equifax and TransUnion and check your credit reports regularly for accuracy.
Alternatives to Credit Counselling
If counselling isn’t the right fit, consider these alternatives:
- Debt consolidation loans – Combine multiple debts into one loan with a single monthly repayment.
- Consumer proposals – Legally reduce unsecured debts through a Licensed Insolvency Trustee.
- Personal loans – May be suitable for borrowers who need to cover a one-time expense or consolidate a smaller amount of debt.
- Lines of credit – A flexible borrowing option that allows you to access funds as needed and only pay interest on the amount you use.
- Budget coaching or financial planning – Ideal for improving long-term money management and preventing future debt problems.
Each option has advantages and disadvantages. Before choosing a debt solution, compare the costs, eligibility requirements and potential impact on your finances to determine which approach best suits your circumstances.
How to Choose a Trusted Credit Counselling Agency
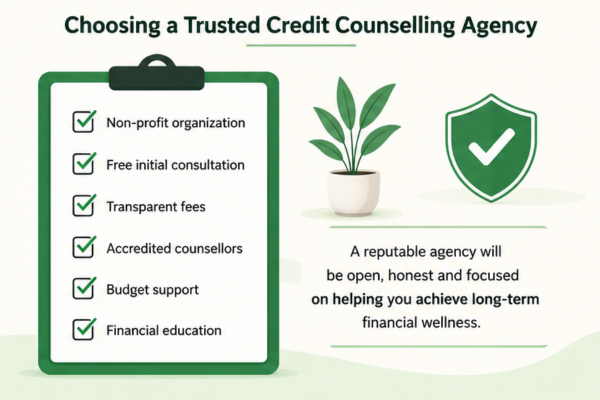
Not every organization offering debt advice provides the same level of service. Before working with any agency, take time to research its credentials and understand exactly what services are offered.
Look for organizations that:
- Operate as registered non-profit organizations.
- Provide free initial consultations.
- Clearly explain any fees before you enrol in a program.
- Employ trained and accredited credit counsellors.
- Do not guarantee debt elimination or instant credit repair.
- Offer budgeting and financial education alongside debt management services.
You can also review guidance published by the Financial Consumer Agency of Canada (FCAC) before selecting a debt relief provider.
Frequently Asked Questions (FAQs) – Credit Counselling & Debt Management
Is credit counselling free in Canada?
Many non-profit credit counselling agencies in Canada offer free initial consultations to review your financial situation. If you enrol in a Debt Management Plan (DMP), there may be a small monthly administrative fee, which is usually included in your repayment plan and disclosed upfront.
How long does credit counselling take?
The counselling session itself may take one to two hours. If you proceed with a Debt Management Plan, repayment programs typically last three to five years, depending on the amount of debt and agreed-upon payment terms.
Can credit counselling stop collection calls?
In many cases, yes. If creditors agree to participate in your Debt Management Plan, collection activity is often reduced and you may receive fewer collection calls. However, this is not guaranteed and depends on the participating creditor’s policies.
Can I still apply for loans while in credit counselling?
Possibly. Some lenders may approve loans based on income stability and affordability, but access to new credit is often limited during a Debt Management Plan. Approval depends on the lender’s policies and your overall financial profile.
Does credit counselling eliminate debt?
No. Credit counselling does not erase or forgive debt. Instead, it helps you repay what you owe in a more structured and affordable way, often by reducing interest rates and consolidating payments into one monthly amount.
Is free credit counselling available in every province?
Many non-profit organizations provide free initial consultations throughout Canada. Services are available in every province, although some northern communities may rely on telephone or virtual appointments.
Will credit counselling reduce my interest rates?
Where appropriate, a credit counsellor may negotiate with participating creditors to reduce or eliminate interest as part of a Debt Management Plan. This depends on the creditor’s policies and your individual circumstances.
How do I know if a credit counselling agency is legitimate?
Choose an accredited non-profit organization that clearly explains its services, provides transparent information about fees and avoids making unrealistic promises about eliminating debt or repairing your credit.
Can I leave a Debt Management Plan?
Debt Management Plans are voluntary arrangements. If your circumstances change, discuss your options with your credit counselling agency before making any decisions.
Final Thoughts: Is Credit Counselling Canada Right for You?
Free credit counselling can be an excellent first step if you’re struggling with debt and want professional guidance before choosing a debt solution. Many non-profit organizations across Canada offer free initial consultations to help you understand your options and build a plan that works for your financial situation.
Ready to Take Control of Your Finances?
Whether you decide that credit counselling, a Debt Management Plan or another debt solution is right for you, taking action early can make managing debt much easier.
At FatCat Loans, we help Canadians explore responsible borrowing options, compare debt consolidation loans and access trusted financial resources to make informed decisions.
Disclosure: This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.


