LendDirect Review Canada 2026: Rates, Loans & Eligibility
March 09, 2022
Our Review of LendDirect Canada
Last Updated: September 2026
This LendDirect review Canada looks at how the lender works, its current Line of Credit and Secured Loan, borrowing costs, eligibility requirements, credit checks and funding times.
LendDirect currently offers two main borrowing products:
- a Line of Credit of up to $10,000
- a Secured Loan of up to $25,000
The Line of Credit is the more flexible option. You apply for a credit limit and can borrow from the available balance when needed rather than receiving the full amount as a one-time loan.
LendDirect currently publishes a 34.99% APR for its Line of Credit. Its Secured Loan has published APRs of 24.99%, 29.99% or 34.99%, depending on the offer you qualify for.
Our view: LendDirect provides flexible access to credit and clearly publishes its current APRs. However, its borrowing rates can be considerably higher than some traditional bank products. Compare the total borrowing cost and repayment structure before accepting an offer.
If you want to research alternatives first, you can compare lenders through the FatCat Loans lender network.
LendDirect at a Glance
| Feature | LendDirect |
|---|---|
| Main product | Personal Line of Credit |
| Line of Credit limit | Up to $10,000 |
| Line of Credit APR | 34.99% |
| Secured Loan | Up to $25,000 |
| Secured Loan APR | 24.99%, 29.99% or 34.99% |
| Pre-approval | Soft credit check |
| Accepting an offer | Hard credit inquiry |
| Line of Credit application | Online, by phone or at a branch |
| Secured Loan application | At a branch |
| Fastest advertised funding | As little as 15 minutes with Interac e-Transfer |
| Minimum age | 18+ |
| Minimum monthly income | $1,000 |
| Credit reporting | Payment history reported to Equifax Canada |
Product details were reviewed in September 2026. Your approved amount and terms depend on your application and LendDirect’s assessment.
What Is LendDirect?
LendDirect is a Canadian lender offering personal Lines of Credit and vehicle-secured loans.
Its main product is an unsecured personal Line of Credit.
Unlike a traditional personal loan, you don’t necessarily borrow your entire approved limit at once. Instead, you can access funds from your available credit as needed.
For example, being approved for a $5,000 credit limit doesn’t mean you have to borrow $5,000. If you draw $1,000, interest is charged on the amount you’ve borrowed.
As you repay your balance, credit may become available to use again without submitting a new application.
LendDirect also offers a Secured Loan backed by your vehicle. This is a different product with different risks, which we’ll cover below.
If you’re comparing revolving credit generally, our Line of Credit Canada page explains how Lines of Credit work and what to compare between providers.
LendDirect Line of Credit
LendDirect currently offers an unsecured Line of Credit of up to:
$10,000
The exact credit limit you’re offered depends on factors including your completed application, income and other qualification requirements.
The main advantage of revolving credit is that you don’t need to submit a new application every time you need to access available funds.
You can:
- get approved for a credit limit
- withdraw an amount from your available credit
- make repayments
- regain available credit as the balance is repaid
- withdraw again when needed, subject to your account remaining available
This makes a Line of Credit different from an installment loan, where you normally receive a set amount upfront and repay it according to an agreed schedule.
How Much Does a LendDirect Line of Credit Cost?
LendDirect currently publishes an annual percentage rate of:
34.99% APR
for its Line of Credit.
You pay interest on the amount you actually borrow rather than your full approved credit limit.
That distinction is important.
If you have a $5,000 limit but only use $1,000, you’re borrowing $1,000 — not $5,000.
However, a revolving Line of Credit can become expensive if you repeatedly draw funds or carry a balance for a long period.
Before accepting an offer, check:
- your approved credit limit
- APR
- amount you’re actually borrowing
- scheduled payment amount
- payment frequency
- how interest is calculated
- any applicable charges
- total cost if you carry the balance for an extended period
At 34.99% APR, it’s particularly important to compare LendDirect with any lower-cost credit you may qualify for.
How Do LendDirect Repayments Work?
LendDirect says payments on its Line of Credit are due on your scheduled income deposits.
Unlike a traditional fixed-term personal loan, a Line of Credit is revolving.
As you repay the balance, available credit can increase again. You can then access that available credit without submitting another application.
This flexibility can be useful for expenses that don’t arrive all at once, but it also makes it possible to remain in debt for longer if you repeatedly use the available credit.
If you’d rather know exactly how much you’ll repay over a fixed period, compare the Line of Credit with personal loans in Canada before deciding.
LendDirect Secured Loans
LendDirect also offers Secured Loans of up to $25,000.
These are different from its unsecured Line of Credit because you use your vehicle as security for the loan.
LendDirect currently publishes three possible APRs for its Secured Loan:
- 24.99%
- 29.99%
- 34.99%
The rate you receive depends on your application and qualification requirements. LendDirect also states that security-search and lien fees apply, with amounts varying by province.
Secured Loans are currently arranged at a LendDirect branch, rather than being a fully online product.
What Does Securing the Loan With Your Vehicle Mean?
Providing security gives the lender a legal interest in the asset used as collateral.
That creates an additional risk for the borrower compared with unsecured credit.
Before accepting a vehicle-secured loan, make sure you understand:
- the APR
- amount borrowed
- repayment schedule
- lien and security-search fees
- total borrowing cost
- what happens if you miss payments
- the lender’s rights over the vehicle if the agreement isn’t repaid
Don’t choose a secured loan simply because it allows you to borrow more.
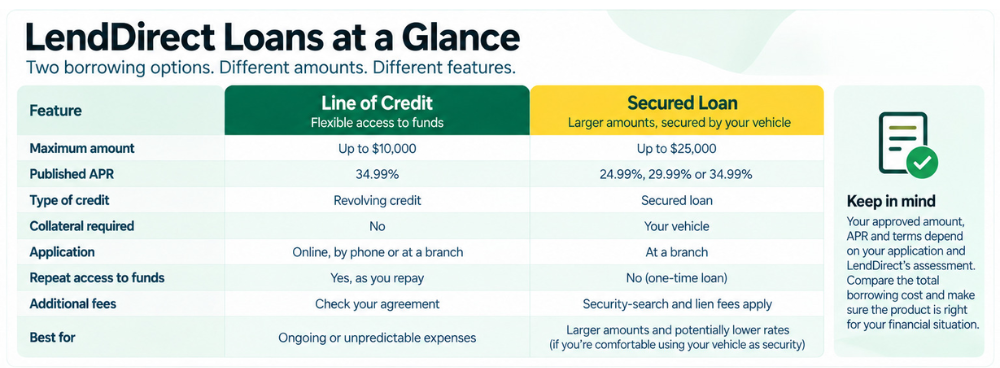
LendDirect Line of Credit vs Secured Loan
| Feature | Line of Credit | Secured Loan |
|---|---|---|
| Maximum advertised amount | Up to $10,000 | Up to $25,000 |
| Type | Revolving credit | Secured loan |
| Published APR | 34.99% | 24.99%, 29.99% or 34.99% |
| Collateral | No | Vehicle |
| Application | Online, phone or branch | Branch |
| Repeat access | Available credit can be reused | No revolving credit limit |
| Additional fees | Check agreement | Security-search and lien fees apply |
| Main risk | Cost of carrying/reusing balance | Vehicle used as security |
A lower advertised APR on a Secured Loan doesn’t necessarily mean it will be the most suitable or lowest-cost option overall.
The products work differently, and putting your vehicle up as security creates a risk that doesn’t apply to the unsecured Line of Credit.
Does LendDirect Check Your Credit?
Yes, but there are two stages to understand.
LendDirect says you can check whether you’re pre-approved using a soft credit check. This doesn’t affect your credit score.
Pre-approval isn’t the same as final approval.
If you decide to accept a LendDirect loan offer, the lender says a hard credit inquiry will occur, which may affect your credit score.
The Financial Consumer Agency of Canada explains that hard credit inquiries appear on your credit report and can affect your credit score, while soft inquiries don’t affect your score.
LendDirect doesn’t publish a simple minimum credit score for its Line of Credit.
That means you shouldn’t assume that a particular credit score will guarantee approval or rejection.
Your application is still subject to LendDirect’s lending assessment and verification.
Does LendDirect Report to the Credit Bureaus?
LendDirect says it reports customers’ payment history to Equifax Canada.
That means how you manage the account may become part of your credit history.
LendDirect says responsible use can help build credit history. However, you shouldn’t take out a high-cost credit product solely for the purpose of trying to improve your credit.
Only borrow when the credit itself is appropriate and you can afford the repayments.
LendDirect Eligibility Requirements
To meet LendDirect’s basic eligibility requirements, you must:
- be a Canadian resident aged 18 or older
- live in Alberta, British Columbia, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island or Saskatchewan
- have a monthly income of at least $1,000
- provide the required banking, identification and income information
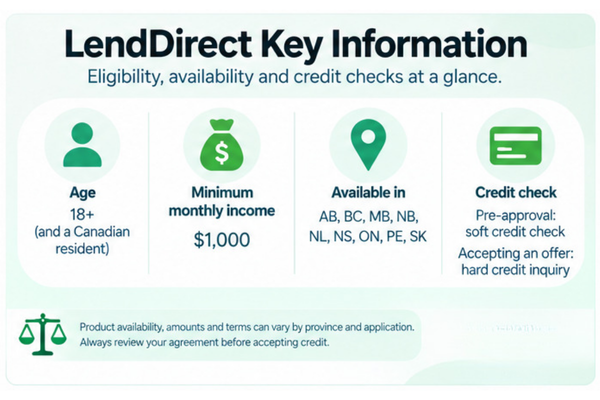
These are basic eligibility requirements and don’t guarantee approval. LendDirect still needs to assess your application before deciding whether to offer credit and how much you may qualify for.
If previous credit problems are limiting your options, you can also compare bad credit loan options in Canada before deciding.
Where Is LendDirect Available?
According to the updated information supplied directly to FatCat Loans by LendDirect, its products are currently available in:
- Alberta
- British Columbia
- Manitoba
- New Brunswick
- Newfoundland and Labrador
- Nova Scotia
- Ontario
- Prince Edward Island
- Saskatchewan
Product and branch availability can differ by province.
For example, LendDirect’s Line of Credit can be available online, by phone or at a branch, while its Secured Loan requires a branch application.
Check availability for your location before starting an application.
How to Apply for LendDirect
The application process depends on the product.
For the Line of Credit, LendDirect currently allows applications online, by phone or at a branch.
The Secured Loan requires you to visit a branch.

Step 1: Check Your Options
Choose whether you’re interested in the unsecured Line of Credit or vehicle-secured loan.
Step 2: Complete the Application
Provide the personal, income, banking and other information requested.
Step 3: Check Pre-Approval
LendDirect says its pre-approval process uses a soft credit check, so checking whether you’re eligible doesn’t affect your credit score.
Remember that pre-approval doesn’t guarantee final approval.
Step 4: Review Your Offer
If you’re offered credit, check:
- the amount or credit limit
- APR
- repayment requirements
- payment dates
- fees
- total borrowing cost
- whether collateral is required
If you accept an offer, LendDirect says a hard credit inquiry will occur.
Step 5: Receive Your Funds
Approved borrowers can receive funds using available funding methods such as Interac e-Transfer.
If you’re comparing lenders with digital application processes, see our guide to online loans in Canada.
How Fast Is LendDirect Funding?
LendDirect advertises funding in as little as 15 minutes when using Interac e-Transfer.
That doesn’t mean every applicant will receive money within 15 minutes.
LendDirect states that lending decisions depend on receiving complete application information and its operating hours. Funding is also subject to bank processing and system availability.
It’s therefore better to think of 15 minutes as the fastest advertised funding time, not a guaranteed payout time.
LendDirect Pros and Cons
Pros
Revolving access to credit
Once approved, you can access available credit without applying for a new loan each time.
Only borrow what you need
You don’t have to withdraw your full approved Line of Credit limit.
Soft-check pre-approval
Checking whether you’re pre-approved doesn’t affect your credit score.
Fast advertised funding
Interac e-Transfer funding may be available in as little as 15 minutes for approved borrowers.
Published APRs
LendDirect clearly publishes its current Line of Credit and Secured Loan APRs.
Cons
34.99% Line of Credit APR
This can be considerably more expensive than lower-rate credit available to borrowers who qualify elsewhere.
Revolving debt can last longer
Repeatedly accessing your available balance can extend the amount of time you remain in debt and increase your total interest cost.
Hard inquiry when accepting an offer
LendDirect says accepting an offer results in a hard credit inquiry.
Secured Loan puts your vehicle at risk
The vehicle is used as collateral, creating an additional risk if you can’t meet your obligations.
Not available throughout Canada
LendDirect operates in selected provinces rather than nationwide.
Is LendDirect Legit?
LendDirect is an established Canadian lender offering Lines of Credit and Secured Loans in several provinces.
Its website provides information about its:
- credit limits
- APRs
- credit-check process
- funding
- repayment
- provincial licences
- Secured Loan fees
LendDirect also publishes applicable provincial licensing information on its website.
However, lender legitimacy and loan affordability are different questions.
A legitimate credit product can still be expensive or unsuitable for your financial circumstances.
The more useful question is whether the APR, repayment structure and risks of the particular LendDirect product make sense for you.
LendDirect vs Other Loan Options
LendDirect’s main point of difference is its revolving Line of Credit.
That makes it more useful to compare LendDirect with other Lines of Credit than with payday loans or products that provide a one-time lump sum.
Before accepting a LendDirect offer, compare:
- APR
- available credit
- payment frequency
- repayment structure
- total borrowing cost
- credit-check requirements
- whether collateral is required
- fees
- early-repayment terms
- consequences of missing payments
A bank or credit-union Line of Credit may offer a lower interest rate if you qualify.
A personal or installment loan may make more sense if you need a specific amount and prefer a fixed repayment schedule rather than reusable credit.
If you want to compare providers before approaching one lender, you can explore the FatCat Loans lender network.
Alternatives to LendDirect
LendDirect isn’t the only option for borrowing.
Depending on your circumstances, alternatives can include:
- a bank or credit-union Line of Credit
- a lower-interest personal loan
- an installment loan with fixed payments
- overdraft protection for a short-term cash shortage
- an existing credit card
- asking a service provider about a payment plan
- using emergency savings
The cheapest suitable option is generally more important than getting access to the largest possible credit limit.
If you already have several debts and are considering a LendDirect product to combine them, compare the new APR and total borrowing cost with your existing debts before proceeding.
Taking out new credit doesn’t automatically make existing debt cheaper.
What Happens If You Miss a LendDirect Payment?
The consequences depend on your product, agreement and circumstances.
Rather than assuming a specific late fee or reporting timetable, check the agreement you’re offered for:
- missed-payment consequences
- possible fees
- interest
- credit reporting
- collection procedures
- what happens to your available credit
- additional consequences if your loan is secured against your vehicle
LendDirect reports payment history to Equifax Canada, so your account activity may become part of your credit history.
If you think you won’t be able to make a scheduled payment, contact LendDirect before the payment date to ask what options may be available.
What Should You Check Before Borrowing From LendDirect?
Before accepting an offer, make sure you understand:
- Which LendDirect product you’re getting
- How much you’re borrowing
- Your APR
- How interest is calculated
- How much and how often you must repay
- The likely total borrowing cost
- Whether any fees apply
- Whether a hard credit inquiry will occur
- Whether your vehicle is being used as security
- What happens if you miss a payment
With a Line of Credit, also think about how you plan to use the account.
The ability to borrow again without reapplying is convenient, but repeatedly drawing funds can keep the balance outstanding and increase your overall borrowing cost.
Frequently Asked Questions About LendDirect
Is LendDirect a legitimate lender?
LendDirect is an established Canadian lender offering Lines of Credit and Secured Loans in several provinces. Its website publishes current product costs, lending information and applicable provincial licence details. You should still check whether the particular product and borrowing cost are suitable for you.
How much can I borrow from LendDirect?
LendDirect currently offers a Line of Credit of up to $10,000 and Secured Loans of up to $25,000. The amount you qualify for depends on your application and LendDirect’s assessment.
What interest rate does LendDirect charge?
LendDirect currently publishes a 34.99% APR for its Line of Credit. Its Secured Loans have published APRs of 24.99%, 29.99% or 34.99%, depending on the offer. Security-search and lien fees also apply to Secured Loans.
Does LendDirect check your credit?
Yes. LendDirect says its pre-approval process uses a soft credit check, which doesn’t affect your credit score. If you accept a loan offer, a hard credit inquiry will occur, which may affect your score.
What credit score do you need for LendDirect?
LendDirect doesn’t publish a simple minimum credit score for its Line of Credit. Applications are subject to its qualification requirements and credit assessment, so a particular credit score doesn’t guarantee approval.
How quickly can I receive money from LendDirect?
LendDirect advertises funding in as little as 15 minutes using Interac e-Transfer. Funding isn’t guaranteed within 15 minutes and can depend on approval, operating hours, bank processing and system availability.
Our Verdict: Is LendDirect Worth Considering?
LendDirect offers something different from a standard personal loan.
Its Line of Credit of up to $10,000 gives approved borrowers revolving access to available credit, while its Secured Loan of up to $25,000 provides access to a larger amount for borrowers willing and eligible to use a vehicle as security.
The lender is also transparent about several important details, including its published APRs, soft-check pre-approval process and the hard credit inquiry that occurs if an offer is accepted.
However, cost remains important.
The Line of Credit currently carries a 34.99% APR, while the Secured Loan can also reach 34.99% and introduces the additional risk of using your vehicle as collateral.
LendDirect may be worth comparing if you need revolving credit, understand the costs and can comfortably meet the repayment requirements.
It may be less suitable if you qualify for a significantly cheaper bank or credit-union product, want a traditional fixed-payment loan, or would struggle to repay the balance without repeatedly drawing from the available credit.
Compare the APR, repayment structure, total borrowing cost and alternatives before accepting an offer.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.