XCash Review Canada 2026: Loans, Rates, Fees & Eligibility
September 14, 2026
Our Review of XCash Canada
Last Updated: September 2026
If you’re considering borrowing from XCash, this XCash review Canada explains how the lender works, the types of loans available, current borrowing costs and what you should check before applying.
XCash Financial Services Inc., trading as XCash Money Solutions, is an Ontario lender offering several forms of borrowing. These include unsecured personal loans, payday loans, home equity loans, car title loans and loans secured against gold.
For most borrowers researching XCash online, the two products most likely to be relevant are its personal loans and payday loans. They work very differently and should not be confused.
Our view: XCash provides clear information about many of its current loan costs and identifies its Ontario payday-loan licence. However, its unsecured personal-loan APR is currently close to 35%, while payday loans can be particularly expensive when their short-term cost is expressed as an annual percentage rate. Compare the actual cost and repayment structure carefully before borrowing.
If you’d rather compare providers before approaching one lender, you can compare lenders through the FatCat Loans lender network.
XCash at a Glance
| Feature | XCash |
|---|---|
| Provider | XCash Financial Services Inc. |
| Location | North York, Ontario |
| Personal loan amount | Up to $5,000 |
| Personal loan APR | 34.56%–34.95% |
| Personal loan terms | 6, 12, 18 or 24 months |
| Personal loan payments | Bi-weekly |
| Personal loan collateral | None |
| Minimum published credit score | None |
| Early repayment penalty | None on personal loans |
| Payday loan amount | $100–$1,500 |
| Payday loan cost | $14 per $100 borrowed |
| Payday loan availability | Ontario |
| Application | Online |
| Payday lender licence | Ontario licence # B82-4868768 |
These details come from XCash’s current website and disclosures as reviewed in September 2026. Loan terms and eligibility can change, so check the agreement offered to you before accepting a loan.
What Is XCash?
XCash Money Solutions is a lender based in North York, Ontario. According to XCash, it has operated since 2008 and offers five main borrowing options:
- payday loans
- unsecured personal loans
- home equity loans
- car title loans
- loans secured against gold
XCash describes itself as a lender rather than a loan broker, meaning someone applying directly to XCash is applying for one of its products rather than having an application distributed to a network of different lenders.
That distinction matters. If your objective is to compare different providers instead, you can explore personal loan options in Canada through FatCat Loans.
This review focuses mainly on XCash’s unsecured personal and payday loans because they are the products most relevant to readers researching short-term and personal borrowing.
XCash Personal Loans
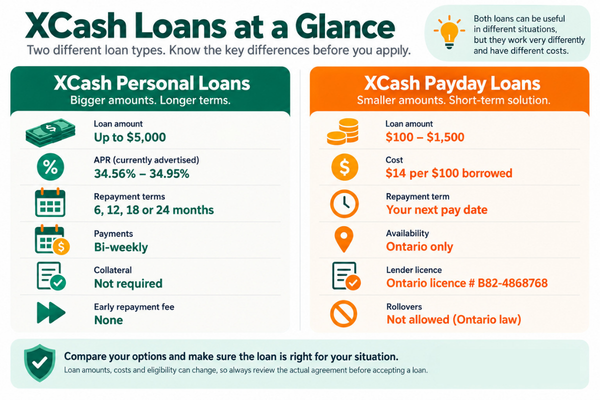
XCash currently offers unsecured personal loans of up to $5,000.
Because these loans are unsecured, you don’t need to pledge your house, car or another asset as collateral.
XCash currently lists repayment terms of:
- 6 months
- 12 months
- 18 months
- 24 months
Payments are made bi-weekly and are designed to follow the borrower’s pay dates. XCash also says there is no prepayment fee, so borrowers can repay the personal loan early without a penalty.
If this is the type of borrowing you’re looking for, our installment loans in Canada page explains how loans repaid through scheduled installments work.
What APR Does XCash Charge on Personal Loans?
This is one of the most important parts of the review.
XCash currently publishes a personal-loan APR range of:
34.56%–34.95% APR
That is a narrow range and is close to Canada’s current 35% criminal interest-rate threshold for most loans.
Canada’s criminal interest rate was reduced to 35% APR on January 1, 2025, subject to specific exceptions, including rules that apply to payday loans. The Financial Consumer Agency of Canada (FCAC) explains that the change was introduced alongside a $14-per-$100 cap on payday-loan borrowing costs.
Don’t choose a loan simply because the payment appears manageable. A longer repayment period can reduce the size of individual payments while increasing the length of time you remain in debt.
Before accepting an XCash personal loan, check:
- the amount borrowed
- APR
- bi-weekly payment
- number of payments
- total interest and other borrowing costs
- total amount repayable
XCash gives an example of a $2,500 personal loan over 24 months, with payments of $67.13 bi-weekly. Treat this as an example rather than a quote for your own application.
XCash Payday Loans
XCash also offers payday loans, but these are fundamentally different from its personal installment loans.
Its current payday loans range from:
$100 to $1,500
and are generally repaid on the borrower’s next payday.
XCash gives the example of borrowing $300 for 14 days. The borrowing cost is $42, meaning the borrower repays $342. XCash displays the equivalent APR as 365%.
That extremely high annualized percentage illustrates why payday loans should not be compared with ordinary personal loans based solely on the dollar fee.
How Much Does an XCash Payday Loan Cost?
Ontario currently limits the maximum cost of a payday loan to:
$14 for every $100 borrowed.
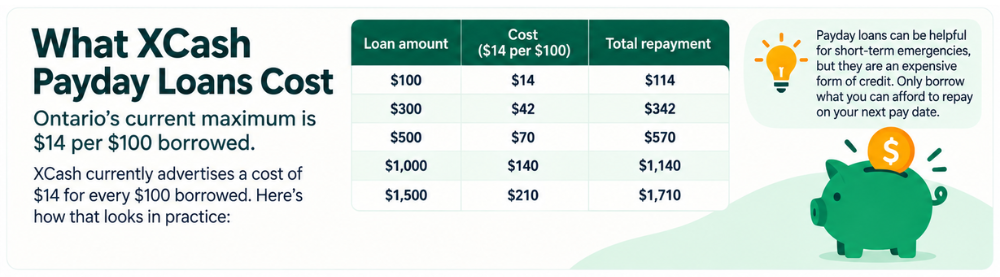
These examples assume the maximum $14-per-$100 charge and don’t represent personal installment-loan pricing.
The Government of Ontario confirms that payday lenders cannot charge more than $14 for every $100 borrowed. Ontario also gives payday-loan borrowers two business days to cancel an agreement without a penalty or reason, and rollover payday loans are prohibited.
Ontario also requires lenders to offer an extended payment plan if you take out three payday loans from the same lender within a 63-day period. This allows repayment to be spread across multiple pay periods, subject to Ontario’s rules.
XCash Personal Loan Eligibility
According to XCash’s current personal-loan requirements, applicants must:
- be 18 or older
- be a Canadian resident
- currently be employed full-time with steady income
- have a chequing account open for at least three months
XCash gives different information about its minimum credit score. Its personal-loan page says there is no minimum score. However, its Terms and Conditions say personal loans are offered to borrowers with a credit score of 600 or higher.
XCash also says a credit check is required and approval is not guaranteed. Because the information differs across its website, check the current requirements with XCash before applying.
Meeting those requirements does not guarantee approval.
If previous credit problems are limiting your options, you can also compare bad credit loan options in Canada. Compare APRs and total repayment costs carefully because borrowing with weaker credit can be expensive.
Does XCash Check Your Credit?
This needs some care because XCash offers several products with different assessment methods.
XCash states that there is no minimum credit score for its personal loans. However, one of its current loan disclosures says personal/installment-loan eligibility includes a credit check and that all loans are subject to credit approval.
Therefore, XCash personal loans shouldn’t be described as “no credit check loans.
Other secured XCash products can work differently. Its gold/pawn product, for example, is advertised as not requiring a credit check.
If avoiding a traditional credit assessment is important to you, our guide to no credit check loans in Canada explains what that term can mean and what to check before applying.
How to Apply for an XCash Loan
XCash offers an online application process.
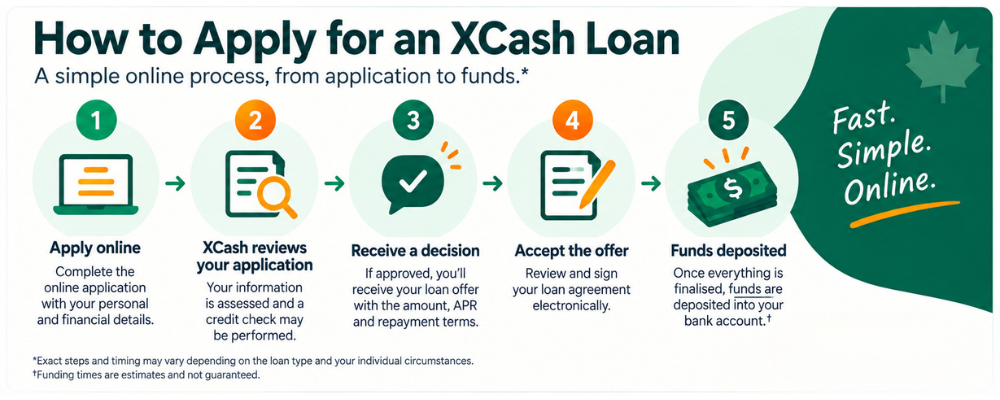
Step 1: Choose the Loan Type
Start by deciding whether you’re looking for a personal loan, payday loan or another XCash product.
Don’t choose solely according to which option appears fastest. The repayment structure and total cost are more important.
Step 2: Complete the Application
Provide the requested personal, employment, income and banking information.
XCash’s requirements vary according to the product.
Step 3: XCash Reviews the Application
XCash assesses whether you meet its eligibility and lending requirements.
Approval is not guaranteed.
Step 4: Review the Offer
If you’re offered a loan, check the agreement carefully before accepting it.
Look particularly at the:
- APR or borrowing cost
- repayment amount
- payment frequency
- loan term
- total amount repayable
- missed-payment consequences
Step 5: Receive the Funds
Funding times depend on the product and successful completion of XCash’s requirements.
XCash says payday loans are generally funded the same day following approval, often within a few hours. Personal-loan funding is generally stated as one to two business days. These are XCash’s advertised timings rather than guaranteed funding times.
If you prefer a digital application, you can also compare online loans in Canada before choosing a provider.
XCash Pros and Cons
Pros
Several loan types
XCash offers unsecured and secured borrowing options rather than a single loan product.
Published personal-loan APR
The current 34.56%–34.95% APR range is disclosed on XCash’s website.
No published minimum credit score
XCash says it considers more than a credit-score number when assessing personal-loan applicants.
No personal-loan prepayment penalty
Borrowers can repay an XCash personal loan early without a prepayment fee.
Ontario payday-loan licence displayed
XCash publishes Ontario payday lender licence # B82-4868768 on its website.
Cons
Personal loans are expensive
The currently advertised APR of 34.56%–34.95% is high compared with many lower-cost forms of credit.
Maximum personal loan is relatively small
XCash personal loans currently go only up to $5,000.
Full-time employment requirement
XCash currently lists full-time employment with steady income among its personal-loan eligibility requirements.
Payday loans have a very high annualized cost
Although Ontario caps the dollar cost, XCash’s own $300-for-14-days example produces an equivalent 365% APR.
Primarily Ontario-focused
XCash describes itself as serving Ontarians and its payday lending licence is Ontario-specific.
Is XCash Legit?
XCash appears to be an established Canadian lending business rather than an anonymous online loan website.
The company identifies itself as XCash Financial Services Inc., provides a North York address and telephone number, and says it has operated since 2008. It also publishes Ontario payday lender licence # B82-4868768.
The Better Business Bureau also has a profile for XCash at the same Bathurst Street address. However, XCash is not BBB accredited, and the BBB currently says it doesn’t have enough information to issue the business a rating. BBB accreditation isn’t required for a lender to operate.
XCash also currently has a Trustpilot profile, but it has only two reviews, which is far too small a sample to draw meaningful conclusions about overall customer experience.
For payday loans specifically, Ontario recommends checking that a lender is licensed before borrowing.
So rather than asking only whether XCash is “legit,” the more useful question is whether the particular XCash product and offer are appropriate and affordable for you.
XCash Personal Loans vs Payday Loans
These products shouldn’t be treated as interchangeable.
| XCash Personal Loan | XCash Payday Loan | |
|---|---|---|
| Amount | Up to $5,000 | $100–$1,500 |
| Repayment | Bi-weekly over 6–24 months | Generally next payday |
| Published cost | 34.56%–34.95% APR | $14 per $100 borrowed |
| Collateral | None | None |
| Early repayment fee | None | Different payday-loan rules apply |
| Best comparison | Other personal/installment loans | Lower-cost alternatives first |
For someone who qualifies for both, the important comparison isn’t simply which gives you money fastest. Look at how much you’ll repay, how quickly repayment is due and whether the payment fits your budget.
XCash vs Other Loan Options
Before borrowing from XCash, consider whether another source of credit could cost less.
Depending on your circumstances, alternatives might include:
- a bank or credit-union personal loan
- an existing line of credit
- another online personal lender
- a loan comparison service
- asking a service provider about a payment plan for a large bill
Our line of credit Canada page explains how revolving credit differs from a fixed-term loan.
If you want to compare lenders rather than apply directly to XCash, you can compare lenders through the FatCat Loans lender network.
What Should You Check Before Borrowing From XCash?
Before accepting any loan, check the actual agreement rather than relying on the headline loan amount or advertised funding speed.
Make sure you understand:
- How much you’re borrowing
- The APR or cost of borrowing
- How much each payment will be
- When payments are due
- How long you’ll be in debt
- The total amount you’ll repay
- What happens if you miss a payment
- Whether early repayment is allowed
- Whether the payments comfortably fit your budget
For payday loans, also understand your specific rights under Ontario law.
If an Ontario payday loan goes into default, additional rules apply. Ontario currently limits default interest on the outstanding principal to 2.5% per month (non-compounding) and limits the fee for a dishonoured cheque or pre-authorized debit to $20.
If you’re already struggling to meet existing debt payments, repeatedly taking new loans can make the problem harder to manage. Our Debt Consolidation vs Consumer Proposal vs Bankruptcy in Canada guide explains some alternatives when debt has become difficult to manage.
Frequently Asked Questions About XCash
How much can I borrow from XCash?
XCash currently offers unsecured personal loans of up to $5,000 and payday loans from $100 to $1,500. Other secured products have different borrowing limits.
What APR does XCash charge for personal loans?
XCash currently advertises personal-loan APRs from 34.56% to 34.95%. Review your individual loan agreement because your actual borrowing terms depend on the offer you receive.
Does XCash have a minimum credit score?
XCash says it doesn’t have a published minimum credit-score requirement for its personal loans. It considers the applicant’s broader financial circumstances, and approval is not guaranteed.
Does XCash perform a credit check?
XCash’s current disclosure says personal/installment-loan eligibility includes a credit check and that loans are subject to credit approval. Credit-check requirements can differ for its secured products.
How much does an XCash payday loan cost?
XCash currently advertises a cost of $14 for every $100 borrowed for its payday loans. This is also Ontario’s current maximum permitted payday-loan borrowing cost. A $300 loan at that rate would cost $42, making the total repayment $342.
Can I repay an XCash personal loan early?
Yes. XCash says its personal loans have no prepayment fee, allowing borrowers to repay early without a penalty.
Our Verdict: Is XCash Worth Considering?
XCash has some positive transparency signals. It publishes its personal-loan APR range, provides eligibility information, displays its Ontario payday-loan licence and explains the costs of its payday loans.
But the cost deserves close attention.
Its personal loans currently carry APRs of 34.56%–34.95%, while payday loans are a particularly expensive form of short-term borrowing when their cost is annualized.
XCash may be worth comparing for an Ontario borrower who understands the costs, meets the eligibility requirements and can comfortably afford the scheduled repayments.
It may be less suitable if you’re able to qualify for substantially cheaper credit elsewhere or if taking another loan would worsen an existing debt problem.
The decision shouldn’t come down to how quickly XCash can provide money. Compare the total cost, repayment schedule and alternatives before accepting an offer.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.