goPeer Review Canada 2026: Rates, Fees, Eligibility & Pros and Cons
October 28, 2026
Is goPeer a Good Personal Loan Option in Canada?
Last Updated: October 2026
In this goPeer review Canada 2026, we examine how the company’s peer-to-peer personal loans work, including interest rates, origination fees, eligibility requirements, funding times and customer complaints.
goPeer offers an alternative to borrowing directly from a traditional bank. Its online platform connects eligible Canadian borrowers with investors who fund personal loans. However, this does not automatically make borrowing cheaper, easier or faster.
Advertised annual percentage rates (APRs) range from 8.99% to 34.99%, and an origination fee is deducted from the loan proceeds. The amount you qualify for and the total cost depend on your individual application.
If you’re comparing several providers, start with our personal loans in Canada guide to understand the main types of borrowing available.
goPeer Loans: Quick Overview
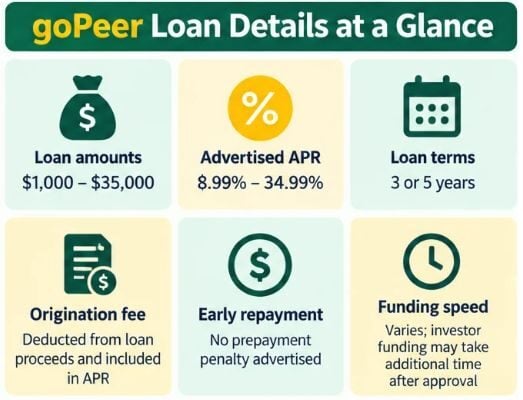
| Feature | goPeer Details |
|---|---|
| Company | goPeer |
| Website | gopeer.ca |
| Loan type | Unsecured peer-to-peer personal loans |
| Advertised loan amounts | $1,000–$35,000 |
| Advertised APR | 8.99%–34.99% |
| Loan terms | 3 or 5 years |
| Origination fee | Yes; deducted from loan proceeds and included in APR |
| Early repayment penalty | None advertised |
| Unsuccessful payment fee | $50 per returned payment attempt |
| Late payment fee | Greater of $25 or 5% of the unpaid instalment, under the published fee policy |
| Funding speed | Varies; investor funding may take additional time after approval |
| Availability | Advertised across Canada, subject to provincial lending rules and eligibility |
Source: goPeer’s published loan disclosures and borrower-fee information, reviewed October 2026. These are advertised terms, not a personalized loan offer. Confirm all figures before signing.
What Is goPeer and How Does It Work?
goPeer is a Canadian peer-to-peer lending platform. Instead of relying solely on a bank to provide loan capital, its model allows investors to fund loans made available through the platform.
For borrowers, the experience resembles an online personal loan application. You provide information about your finances, go through an assessment and may receive an offer setting out the borrowing terms.
The main difference is that an accepted loan must also go through the platform’s investor-funding process.
How the goPeer Loan Process Works
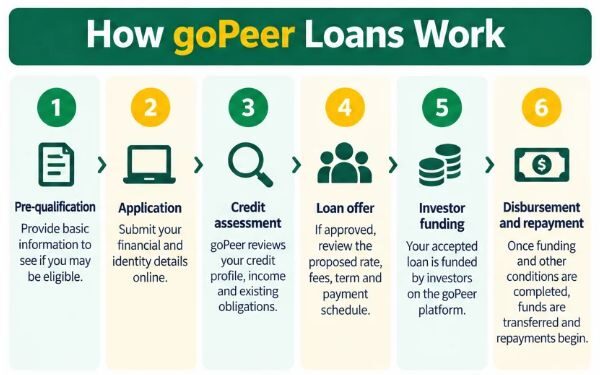
- Pre-qualification: Provide initial information to see whether you may be eligible.
- Application: Submit the financial and identity details needed for assessment.
- Credit assessment: Your credit profile, income, existing obligations and ability to repay are evaluated.
- Loan offer: If approved, review the proposed rate, fees, term and payment schedule.
- Investor funding: The accepted loan enters the platform’s funding process.
- Disbursement and repayment: Once funding and other conditions are completed, proceeds are transferred and scheduled repayments begin.
Approval and investor funding are separate stages. An approved application does not necessarily mean that money is immediately available.
goPeer Interest Rates and Loan Amounts
goPeer advertises unsecured personal loans ranging from $1,000 to $35,000, with repayment terms of three or five years.
Its advertised APR range is 8.99% to 34.99%. The rate offered to an individual borrower depends on the lender’s assessment of creditworthiness, financial circumstances and ability to service the debt.
APR is particularly important when reviewing goPeer because the platform charges an origination fee.
Interest Rate vs. APR
The interest rate describes the cost of borrowing the principal. APR is a broader annual measure that can include applicable borrowing fees.
goPeer states that its advertised APR includes both interest and the origination fee. Therefore, comparing only its stated interest rate with another lender’s APR could give a misleading impression of which loan costs less.
Canada’s general criminal-interest threshold is 35% APR, subject to applicable statutory and regulatory exceptions. That threshold is not a recommended borrowing rate or a guarantee of affordability.
What Fees Does goPeer Charge?
goPeer’s fee structure is one of the most important parts of this review. Although the platform advertises no early repayment penalties, borrowers should understand its origination and missed-payment charges.
1. Origination Fee
goPeer charges a one-time origination fee that is deducted from the loan proceeds. The company states that this fee is included in the disclosed APR and does not have to be paid upfront.
For example, if an approved loan had a principal amount of $10,000 and a hypothetical $400 origination fee, the borrower would receive $9,600 before any other applicable adjustments.
This is a hypothetical example, not goPeer’s published fee percentage. The actual deduction must be confirmed in your individual loan offer.
Check the difference between the amount you agree to repay and the cash that will arrive in your bank account.
2. Unsuccessful Payment Fee
goPeer publishes a $50 fee when an automatic payment is rejected, such as when the linked account has insufficient funds.
Its fee policy also states that a payment may be attempted up to two additional times, with a fee potentially applying to each returned attempt.
Repeated failed withdrawals could therefore increase borrowing costs. Ask about the available arrangements if you anticipate difficulty making a scheduled payment.
3. Late Payment Fee
goPeer’s detailed borrower-fee page describes a 15-day grace period, followed by a late fee that may be assessed on the 16th day. The published amount is the greater of $25 or 5% of the unpaid instalment.
However, the general loan disclosure on its website describes a late-payment fee for payments 30 or more days late.
These published timing descriptions are not fully consistent. Borrowers should confirm the actual grace period, fee trigger and credit-reporting treatment in the current agreement.
4. Early Repayment
goPeer states that borrowers can make additional payments or repay their loans in full without a prepayment penalty.
Paying early may reduce future interest costs. Nevertheless, the origination fee is already deducted from the original proceeds, so early repayment should not be assumed to reverse that charge.
goPeer Loan Cost Example
Consider a hypothetical $10,000 loan repaid over 36 months at a fixed annual interest rate of 19.99%, with equal monthly payments.
| Loan Detail | Illustrative Amount |
|---|---|
| Loan principal | $10,000 |
| Annual interest rate | 19.99% |
| Repayment term | 36 months |
| Approximate monthly payment | $371.58 |
| Approximate total repayment | $13,377 |
| Approximate interest cost | $3,377 |
This is an illustrative amortization calculation using a nominal annual interest rate and monthly payments, not a goPeer quote. It excludes origination fees and other charges. A goPeer offer quoting 19.99% APR rather than 19.99% interest would require a different calculation because its APR includes the origination fee.
Before accepting any offer, compare the actual cash received, the payment schedule, the APR and the total amount repayable.
Who Qualifies for a goPeer Personal Loan?
goPeer assesses applications using credit and financial information. Approval is not automatic, and the lowest advertised APR will not be available to everyone.
Applicants should expect to provide or verify information such as:
- Identity and Canadian residency
- Employment or other verifiable income
- Credit history and existing financial obligations
- Bank account information
- Additional supporting documents, where required
goPeer’s eligibility criteria may include minimum credit and income requirements. Before applying, check the current criteria directly with goPeer, as eligibility requirements and assessment methods can change.
Can You Get a goPeer Loan With Bad Credit?
Borrowers with weaker credit histories may find it harder to qualify or may receive less favourable terms.
Peer-to-peer lending does not mean credit checks or affordability assessments disappear. Investors and the platform still need to evaluate the risk associated with a loan.
If your credit history is a concern, compare the broader market using our bad credit loans guide, while paying close attention to borrowing costs and repayment affordability.
How Long Does goPeer Take to Approve and Fund a Loan?
goPeer advertises an application response within approximately 24–48 hours. However, this should not be confused with guaranteed funding.
The process involves three distinct stages:
- Application review: The platform evaluates your information and may request additional verification.
- Investor funding: An accepted loan must progress through the platform’s funding process.
- Bank transfer: Funds are transferred after the relevant funding and disbursement conditions have been met.
Third-party reviews indicate that investor funding can sometimes take several days or longer. Actual timing may vary significantly between applications.
Consequently, goPeer may not be suitable for someone who must receive money on the same day.
Our online loans guide explains how approval and disbursement times can differ across Canadian providers.
Is goPeer a Legitimate Lending Platform in Canada?
goPeer is a Canadian peer-to-peer lending platform that connects eligible borrowers with investors who fund personal loans.
The company operates through its website, gopeer.ca, where borrowers can find information about loan amounts, interest rates, fees and repayment terms.
However, being an established lending platform does not automatically mean that a loan is suitable or affordable for every borrower.
Before applying, review the company’s current terms, confirm the legal identity of the lender named in your agreement and understand the total borrowing cost, including any origination fees.
For general guidance on assessing personal loan providers, visit the Financial Consumer Agency of Canada.
goPeer Reviews and Customer Feedback
Customer reviews provide useful insight into the borrowing experience, particularly the application process, customer service and time required to receive funds.
On Trustpilot, goPeer has an overall rating of approximately 4.5 out of 5 stars, based on more than 200 customer reviews as of October 2026.
Positive reviewers frequently highlight the straightforward online application, helpful customer support and clear communication about the borrowing process.
However, not all experiences are positive. Some reviewers report longer-than-expected funding times, particularly after receiving an initial loan approval.
Because goPeer uses an investor-funded lending model, approval and disbursement are separate stages. Borrowers should therefore confirm expected funding times before relying on the loan for an urgent expense.
Customer reviews reflect individual experiences and do not guarantee approval, funding speed or satisfaction. Ratings can also change as new reviews are submitted.
goPeer Pros and Cons
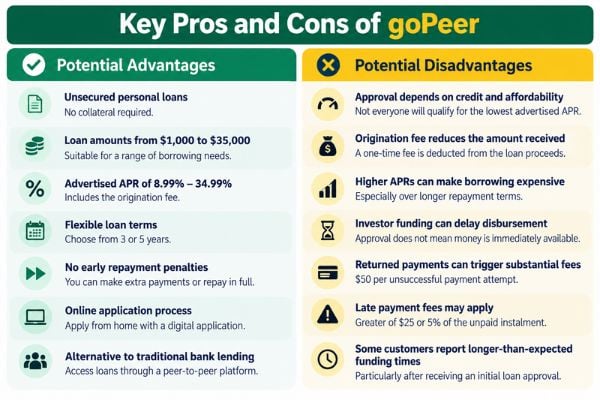
| Potential Advantages | Potential Disadvantages |
|---|---|
| Unsecured loans do not require pledged collateral. | Approval depends on credit and affordability assessment. |
| Advertised borrowing range of $1,000–$35,000. | An origination fee reduces the amount received. |
| Published APR includes the origination fee. | Higher APRs can make longer-term borrowing expensive. |
| No advertised early repayment penalties. | Investor funding can delay disbursement. |
| Online application process. | Returned payments can trigger substantial fees. |
| Alternative to conventional bank lending. | Some customers report longer-than-expected funding times. |
How Does goPeer Compare With Traditional Personal Loans?
goPeer’s peer-to-peer model may appeal to Canadians who want an alternative to a conventional bank. However, the funding model alone does not establish whether the loan is better value.
When comparing goPeer with a bank, credit union or another online lender, consider:
- APR: Compare the annual borrowing cost, including applicable fees.
- Net proceeds: Check how much money will actually be deposited after deductions.
- Total repayment: Calculate what you will pay over the entire loan term.
- Funding reliability: Ask whether money is available immediately after approval or only after another funding stage.
- Payment flexibility: Review early repayment, missed-payment and rescheduling terms.
- Provider credentials: Verify the company’s identity and any regulatory claims relevant to its activities.
For a wider comparison, see the information about participating providers in our Canadian lender network. FatCat Loans is a loan-matching service, not the lender issuing any resulting loan.
Who Might Consider goPeer — and Who Should Look Elsewhere?
goPeer May Be Worth Comparing If:
- You want an unsecured personal loan rather than a secured product.
- You can afford scheduled repayments over three or five years.
- You are comfortable with the possibility of waiting for investor funding.
- You have reviewed the origination fee and understand the difference between APR and interest rate.
- You have compared the offer with other available borrowing options.
goPeer May Be Less Suitable If:
- You need guaranteed same-day funding.
- You cannot comfortably manage regular loan repayments.
- You need to receive the full approved principal without an origination deduction.
- You are seeking a short repayment term outside its advertised options.
Borrowing should be based on affordability and a clear understanding of the agreement, not simply whether an application is approved.
Frequently Asked Questions About goPeer Canada
Is goPeer a legitimate lender in Canada?
goPeer is an established Canadian peer-to-peer lending platform with publicly available loan information and fee disclosures. Before accepting a loan, borrowers should verify the lender’s identity, review the agreement and make sure the repayments are affordable.
What interest rates does goPeer charge?
goPeer advertises APRs ranging from 8.99% to 34.99%. The actual APR depends on the borrower’s credit profile, financial circumstances and the loan offer. Its APR includes the origination fee.
Does goPeer charge an origination fee?
Yes. goPeer states that it deducts a one-time origination fee from the loan proceeds and includes that fee in the disclosed APR. The actual amount should appear in the individual loan offer.
How long does goPeer take to fund a loan?
goPeer advertises an application response within approximately 24–48 hours, but funding can take longer because approved loans go through an investor-funding process. Same-day disbursement should not be assumed.
Can I repay a goPeer loan early?
Yes. According to goPeer’s published fee policy, borrowers can make extra payments or repay their loan in full without a prepayment penalty. Review the agreement to confirm how early repayment affects the remaining balance and interest.
Can I get a goPeer loan with bad credit?
Approval depends on goPeer’s assessment of credit history, income, existing debts and repayment affordability. Borrowers with weaker credit profiles may face more limited options or higher borrowing costs, and approval is not guaranteed.
Final Verdict: Is goPeer Worth Considering in 2026?
goPeer provides a distinctive alternative to conventional personal loans in Canada. Its unsecured lending model, advertised APR range and penalty-free early repayment policy may make it worth comparing with other providers.
However, the origination fee, potential funding delays and missed-payment charges are important drawbacks. Although customer feedback is generally positive, some reviewers report delays in receiving their funds.
Our assessment: goPeer may be worth including in a personal-loan comparison, but borrowers should not select it based solely on its advertised starting APR or the appeal of peer-to-peer lending. Confirm the net loan proceeds, full repayment cost, funding conditions and current regulatory information before committing.
For general guidance on evaluating a borrowing agreement, see our Canadian borrower rights guide.
Sources
- goPeer – Official Website and Loan Disclosures
- goPeer – Borrower Fees
- Trustpilot – goPeer Customer Reviews
- Financial Consumer Agency of Canada – Personal Loans
Editorial note: This review is based on publicly available information checked in October 2026. FatCat Loans has not independently tested the application process or obtained a personalized loan offer. Loan terms, fees, funding times and customer ratings can change.
Disclaimer: This article is for general information only and does not constitute financial, legal or investment advice. FatCat Loans is a loan-matching service, not goPeer or a direct lender. Approval, rates, fees and funding depend on the provider and applicant. Always review the current agreement before borrowing.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.