Money Mart Review Canada 2026: Loans, Rates, Fees & Pros and Cons
March 16, 2022
Our Review of Money Mart Canada
Last Updated: September 2026
Money Mart is a Canadian financial services provider offering installment loans, payday loans and other services online and through physical locations.
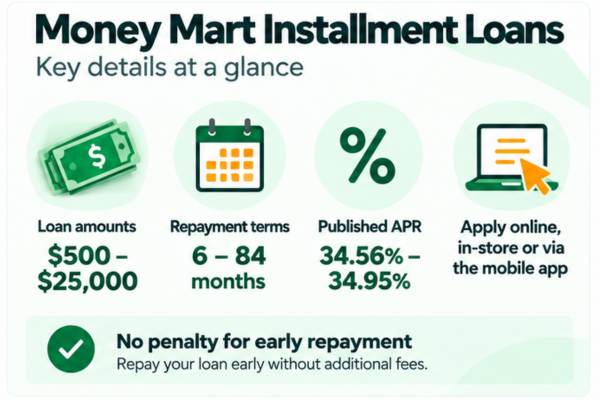
Its installment loans currently range from $500 to $25,000, with repayment terms from 6 to 84 months and advertised APRs between 34.56% and 34.95%. Money Mart also offers payday loans, with costs and availability varying by province.
This Money Mart review looks at its current loan options, borrowing costs, eligibility requirements, credit checks, funding, pros and cons, and alternatives to consider before applying.
Money Mart Canada: Key Facts
| Feature | Current Details |
|---|---|
| Main loan products | Installment loans and payday loans |
| Installment loan amount | $500–$25,000 |
| Installment loan term | 6–84 months, depending on the loan amount |
| Published installment loan APR | 34.56%–34.95% |
| Applications | Online, in-store or through the Money Mart mobile app |
| Credit check | Installment loan approval may require a hard credit inquiry |
| Early repayment | No penalty for paying an installment loan off early |
What Is Money Mart?
Money Mart is a Canadian alternative financial services provider offering borrowing products and other financial services online and through physical locations.
Its main borrowing products include installment loans and payday loans. Money Mart also provides services such as cheque cashing, money transfers, bill payments and prepaid cards at participating locations.
Money Mart isn’t the only borrowing option available. Before applying, compare the total borrowing cost, repayment schedule and eligibility requirements with other personal loans in Canada.
What Loans Does Money Mart Offer?
Installment Loans
Money Mart currently advertises installment loans from $500 to $25,000. Repayment terms range from 6 to 84 months, depending on the amount borrowed.
Its current published APR range is 34.56% to 34.95%. Payments may be scheduled weekly, bi-weekly, monthly or bi-monthly based on your payday schedule.
Money Mart says installment loans can be applied for online, in-store or through its mobile app. Borrowers can also repay an installment loan early without a prepayment penalty.
If you want to compare this type of borrowing with other providers, see our guide to installment loans in Canada.
Payday Loans
Money Mart also offers short-term payday loans, which it currently refers to as Payday Boost in some of its online material.
Payday-loan availability, borrowing limits, repayment periods and costs vary by province. Money Mart currently states that online Payday Boost loans are available to residents of Alberta, British Columbia, Manitoba, Nova Scotia, Ontario and Saskatchewan.
Because payday loans are high-cost, short-term credit, compare the total repayment amount and alternatives before borrowing.
Money Mart Pros and Cons
| Pros | Cons |
|---|---|
| Installment loans up to $25,000 | Published installment loan APRs are 34.56%–34.95% |
| Installment loan terms from 6 to 84 months | Payday loans are a high-cost form of short-term credit |
| Online, mobile and in-store applications available | Approval and loan terms depend on Money Mart’s assessment |
| No penalty for repaying an installment loan early | Payday-loan availability and terms vary by province |
Money Mart Payday Loan Costs
Payday-loan costs vary by province. Money Mart’s current disclosures show a borrowing cost of $14 per $100 borrowed in several provinces, including Ontario and British Columbia.
For example, Money Mart currently gives this Ontario example for a 14-day payday loan:
- Amount borrowed: $500
- Cost of borrowing: $70
- Total repayment: $570
- Advertised APR: 365%
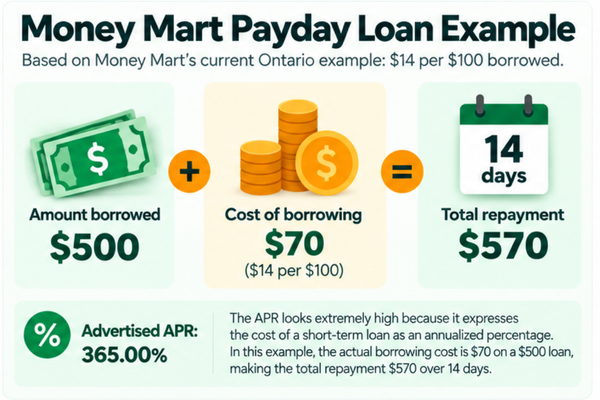
The APR looks extremely high because it expresses the cost of a short-term loan as an annualized percentage. In Money Mart’s 14-day example, the borrowing cost itself is $70 on a $500 loan, making the total repayment $570.
However, payday loans remain an expensive form of credit. Compare the total amount you need to repay, the repayment date and other available borrowing options before accepting one.
The Financial Consumer Agency of Canada (FCAC) explains how payday loans work, their costs and alternatives borrowers may want to consider.
Money Mart Installment Loan Eligibility
Money Mart currently says you can apply for an installment loan if you:
- Are at least the age of majority in your province or territory and have valid identification
- Have a chequing account
- Have a steady source of verifiable income
Money Mart may ask for additional documents or information during the application process.
Meeting these basic requirements doesn’t guarantee approval. Money Mart says it considers several factors when assessing an application, including information in your credit report, the accuracy of your application and potentially your payment history on similar products.
Does Money Mart Check Your Credit?
Money Mart says checking whether you’re eligible for an installment loan can be done without affecting your credit score. However, getting approved for an installment loan may require a hard credit inquiry.
A hard inquiry can temporarily affect your credit score. Money Mart also says your credit report is one of several factors it may consider when assessing an application.
Having weaker credit doesn’t automatically mean you’ll be approved or declined. Eligibility, the amount offered and other loan terms depend on Money Mart’s assessment.
If you’re concerned about your credit history, you can also compare bad credit loan options from other lenders.
How to Apply for a Money Mart Installment Loan
Money Mart allows installment-loan applications online, through its mobile app or at a participating location.
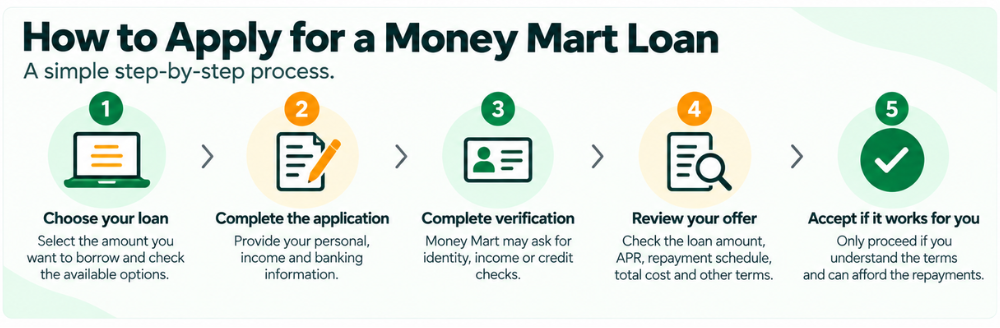
The general process is:
- Choose how much you want to borrow.
- Complete the application with your personal, income and banking information.
- Complete any identity, income or credit checks required by Money Mart.
- If approved, review the loan amount, APR, repayment schedule, total cost and other terms.
- Accept the agreement only if you understand the terms and can afford the repayments.
Approval isn’t guaranteed. Your approved amount and loan terms depend on Money Mart’s assessment.
How Fast Does Money Mart Provide Funds?
Funding time depends on the product, application, funding method and when the application is processed.
Money Mart currently advertises several installment-loan funding methods. Its website says some approved borrowers may receive funds through instant funding in around 15 minutes, while Interac e-Transfer may take up to 24 hours and direct deposit may take 1–2 business days.
These are advertised funding times rather than guarantees. Delays may occur, and funding is subject to approval and Money Mart’s requirements.
Is Money Mart Legit in Canada?
Money Mart is a Canadian financial services provider offering loans and other services online and through physical locations.
Its website publishes product terms, borrowing-cost disclosures and provincial licensing information where applicable. However, borrowers should still review the specific loan agreement carefully because availability, costs and regulatory requirements can vary by product and province.
A lender operating legally doesn’t mean every loan will be suitable or affordable for every borrower. Compare the APR, total cost of borrowing, payment amount and repayment schedule before accepting credit.
If you want to compare Money Mart with other borrowing options, explore the FatCat Loans Canadian lender network before deciding which type of credit suits your needs.
Other Money Mart Services
In addition to loans, participating Money Mart locations advertise other financial services, which may include:
- Cheque cashing
- Money transfers through MoneyGram
- Currency exchange
- Bill payments
- Titanium+ prepaid Mastercard
- Money orders
Availability can vary by location, so check with your local Money Mart before using a specific service.
Alternatives to Money Mart
Money Mart may not be the right option for every borrower. Depending on why you need credit and how long you need to repay it, you may want to compare:
- Need a larger lump sum? Compare personal loans in Canada.
- Want structured repayments? Explore installment loans from other providers.
- Have a weaker credit profile? Compare bad credit loan options.
- Want reusable access to credit? Learn how a line of credit works.
- Want to compare multiple providers? Explore our Canadian lender network.
Payday loans are high-cost credit. If you’re regularly using short-term loans to cover everyday expenses, another loan may not solve the underlying financial problem. A reputable non-profit credit counsellor may be able to help you review other options.
Frequently Asked Questions
How much can I borrow from Money Mart?
Money Mart currently advertises installment loans from $500 to $25,000. Payday-loan amounts vary depending on the province and Money Mart’s lending requirements. Your approved amount isn’t guaranteed.
What APR does Money Mart charge on installment loans?
Money Mart currently advertises installment-loan APRs between 34.56% and 34.95%. Your actual loan terms depend on Money Mart’s assessment and the agreement you’re offered.
Does Money Mart check your credit?
Money Mart says checking installment-loan eligibility can be done without affecting your credit score. However, getting approved may require a hard credit inquiry, which can temporarily affect your score.
How quickly can Money Mart provide loan funds?
Funding depends on the loan, application and funding method. Money Mart advertises instant funding in around 15 minutes for some approved installment-loan borrowers, while Interac e-Transfer and direct deposit may take longer. Funding times aren’t guaranteed.
Can I pay a Money Mart installment loan off early?
Yes. Money Mart currently says there is no penalty for paying an installment loan off early. Check your individual agreement before making additional or early payments.
Are Money Mart payday loans available across Canada?
No. Payday-loan availability varies by province. Money Mart currently states that online Payday Boost loans are available to residents of Alberta, British Columbia, Manitoba, Nova Scotia, Ontario and Saskatchewan. Check Money Mart’s current disclosures because availability can change.
How We Reviewed Money Mart
Our review is based on information published by Money Mart, including its current loan pages, eligibility information, product disclosures and funding information. We also consider guidance from Canadian government and consumer-protection sources when discussing borrowing costs and payday loans.
Loan amounts, APRs, eligibility requirements, availability and funding times can change. Check Money Mart’s current terms and your individual loan agreement before accepting credit.
Final Thoughts
Money Mart offers both longer-term installment loans and short-term payday loans, giving borrowers two very different types of credit to consider.
Its installment loans currently range from $500 to $25,000, with terms from 6 to 84 months and advertised APRs between 34.56% and 34.95%. Payday loans have much shorter repayment periods, and their borrowing costs can translate into very high annualized rates.
Before applying, compare the APR, total cost of borrowing, repayment amount and repayment schedule with other available options. If you’re considering a payday loan, lower-cost alternatives may be worth checking first.
Sources
Disclosure: This article is for informational purposes only and does not constitute financial advice. Loan amounts, APRs, costs, eligibility and availability can vary by lender, product and province. FatCat Loans is a loan comparison platform, not a lender. Always review the lender’s current terms and your loan agreement before accepting credit.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.