NotchUp Canada Review 2026: Fees, Eligibility, Customer Reviews & Alternatives
November 04, 2026
Is NotchUp a Good Cash Advance Option in Canada?
Last Updated: November 2026
In this NotchUp Canada review 2026, we examine how NotchUp works, its advertised $5 wage advance, borrowing limits, eligibility requirements, additional fees, customer reviews and alternatives.
NotchUp is a Canadian financial technology service that allows eligible applicants to access part of their income before their next payday. It advertises advances of up to $1,500, no traditional credit checks and funding by Interac e-Transfer in as little as 15 minutes.
Its main selling point is affordability. NotchUp advertises a flat $5 fee when applicants connect their payroll account. However, other advances may carry variable fees, and its legal disclosures also describe payday-loan borrowing costs.
Customer feedback is another important consideration. Independent reviews include complaints about technical problems, delayed funding and difficulty contacting support.
Before applying, compare the full cost and repayment requirements with other options in our personal loans in Canada guide.
NotchUp Canada: Quick Overview
| Feature | NotchUp Details |
|---|---|
| Company | NotchUp Financial Inc. |
| Official website | notchup.app |
| Product | Wage advances and short-term borrowing products |
| Advertised advance amount | Up to 50% of your next paycheque, subject to a $1,500 maximum |
| Minimum amount in published terms | $50 |
| Advertised standard fee | $5 per advance when payroll verification requirements are met |
| Other borrowing fees | Variable fees may apply without payroll connection; separate legal disclosures describe payday borrowing costs |
| Credit check | No traditional credit check advertised |
| Application | Online, available 24/7 |
| Advertised funding | Interac e-Transfer in as little as 15 minutes |
| Optional subscription | NotchUp Plus, advertised at $11.99 per month |
| Provincial licensing | British Columbia payday lender licence #86443 |
| Availability | Canadian residents may apply, but availability outside British Columbia requires confirmation |
Source: NotchUp’s official website and terms of service, reviewed November 2026. Advertised features are subject to eligibility, product selection and the applicant’s agreement.
What Is NotchUp and How Does It Work?
NotchUp describes itself as an earned wage access service. Rather than waiting until payday, eligible users can request an advance against a portion of their expected income.
The company promotes this as an alternative to conventional payday borrowing, particularly for people facing temporary cash-flow shortages.
NotchUp’s website advertises access to up to 50% of an applicant’s next paycheque, with a maximum advance of $1,500. The amount actually available depends on eligibility and the company’s assessment.
Unlike a traditional personal loan, a wage advance is generally designed to cover a relatively short period until income is received. It is not intended to finance large purchases or long-term borrowing needs.
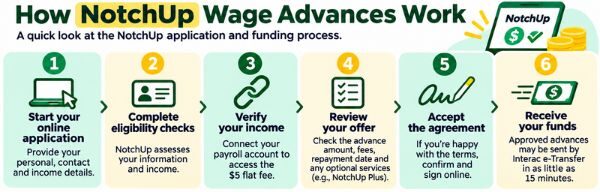
How the NotchUp Application Process Works
- Start an online application: Visit NotchUp’s website and provide the requested personal and income information.
- Complete eligibility checks: The company assesses whether you qualify for an advance.
- Verify your income: Connecting a payroll account may allow access to the advertised $5 fee.
- Review your offer: Check the approved amount, borrowing fee, repayment date and any additional conditions.
- Accept the agreement: Proceed only if the repayment is affordable and you understand the terms.
- Receive funds if approved: NotchUp advertises Interac e-Transfer funding in as little as 15 minutes, although actual processing may take longer.
The company states that applications generally take approximately five to ten minutes to complete. This is an advertised estimate rather than a guarantee of approval or funding.
How Much Can You Borrow From NotchUp?
NotchUp advertises advances of up to 50% of your next paycheque, with a maximum of $1,500.
Its published terms also describe eligible advances starting at $50.
For example, if your next paycheque is expected to be $1,200, the advertised 50% limit would suggest a potential advance of up to $600. However, this is only an illustration. NotchUp may approve a smaller amount or decline an application.
The company also operates a Credit Ladder loyalty program. It says successful on-time repayments may help users move into higher tiers and potentially access larger advances or lower fees.
Credit Ladder availability and benefits can vary, and previous successful repayments do not guarantee approval for another advance.
NotchUp Fees and Borrowing Costs Explained
Understanding NotchUp’s pricing is particularly important because its promotional material and legal disclosures describe different borrowing-cost structures
Does NotchUp Really Charge Only $5?
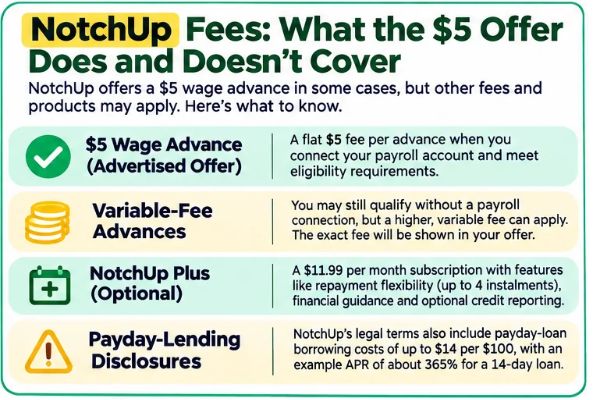
NotchUp advertises a $5 flat fee per wage advance when applicants connect their payroll account and meet the relevant requirements.
Its website also states that applicants who do not connect their payroll account may still qualify for an advance, but a variable fee applies.
The exact variable fee is not clearly specified in the main promotional information reviewed for this article.
Consequently, borrowers should not assume that every NotchUp advance costs $5.
Illustrative Cost of a $5 Wage Advance
| Advance Amount | Advertised Flat Fee | Total Repayment |
|---|---|---|
| $100 | $5 | $105 |
| $250 | $5 | $255 |
| $500 | $5 | $505 |
| $1,000 | $5 | $1,005 |
| $1,500 | $5 | $1,505 |
These are mathematical illustrations of a $5 flat fee, not confirmed offers at every advance amount. They assume the applicant qualifies for the flat-fee arrangement and incurs no additional charges.
Although a flat $5 fee may appear inexpensive, the relative cost is higher on smaller advances.
For example, a $5 fee represents 5% of a $100 advance but only 1% of a $500 advance. Repayment timing also affects the annualized cost.
Why Do NotchUp’s Terms Mention $14 per $100?
NotchUp’s published terms include payday-lending disclosures describing a maximum borrowing cost of $14 per $100 advanced.
Those disclosures include an example of a $500 loan with a $70 borrowing fee over 14 days, producing a total repayment of $570 and an illustrative annual percentage rate of approximately 365%.
This is different from the $5 wage-advance arrangement promoted on the company’s homepage.
The available public information does not establish that every applicant receives the same product or pricing structure. Borrowers should therefore confirm which agreement applies to their offer rather than assuming the advertised flat fee overrides the payday-loan disclosures.
Important: Before accepting an advance, check the total cost of borrowing, repayment schedule, optional subscriptions, overdue charges and any other fees shown in the actual agreement.
What Is NotchUp Plus?
NotchUp also advertises an optional subscription called NotchUp Plus, priced at $11.99 per month.
According to its website, Plus may provide additional features, including:
- The ability to divide repayments into up to four instalments.
- Additional repayment flexibility.
- Access to financial guidance.
- Optional reporting of qualifying payments to support credit building.
The subscription cost is separate from the advertised $5 advance fee. Consumers should check whether a subscription is active, how recurring payments work and how to cancel before enrolling.
Are There Late Payment or NSF Fees?
NotchUp’s published payday-lending terms describe an NSF fee of up to $20 for missed payments and late interest of up to 20% annually on unpaid balances.
Those terms also warn that failure to repay may negatively affect a borrower’s credit history.
Actual charges depend on the applicable agreement and provincial requirements. Borrowers should not assume these provisions apply identically to every NotchUp product.
Who Qualifies for a NotchUp Wage Advance?
NotchUp advertises access for Canadian residents who meet its income and eligibility requirements.
Its website states that applicants with poor credit or limited credit histories may be considered because it does not use a traditional credit score as part of its advertised approval criteria.
However, applicants still need to satisfy the company’s verification and affordability requirements.
Eligibility may depend on:
- Canadian residency and the applicable age requirements.
- Verifiable employment or other eligible income.
- Banking or payroll information sufficient for assessment.
- The amount and timing of expected income.
- The applicant’s repayment capacity and other internal criteria.
NotchUp states that it may consider several income sources, including employment income, Canada Child Benefit payments, CPP, Old Age Security, ODSP, AISH and certain provincial disability benefits.
Acceptance of an income category does not mean every applicant receiving that income will qualify.
Can You Get NotchUp With Bad Credit?
NotchUp advertises no traditional credit checks, which may make it attractive to applicants with damaged or limited credit histories.
However, no credit check does not mean guaranteed approval.
The company may still assess income deposits, banking activity and repayment affordability before making a decision.
If your credit history is affecting your borrowing options, read our bad credit loans in Canada guide.
Our no credit check loans guide also explains how lenders may assess applications without relying on conventional credit scoring.
Which Canadian Provinces Does NotchUp Serve?
NotchUp describes its services as available to Canadians, but its published payday-lending licence disclosure specifically identifies British Columbia.
The company lists British Columbia payday lender licence number 86443, dated January 11, 2024.
Although its website references income benefits associated with other provinces, that does not independently establish that its payday-lending products are licensed or available throughout Canada.
Applicants outside British Columbia should confirm directly with NotchUp which products are available in their province and verify any required lending licence with the relevant provincial regulator.
Provincial consumer-protection rules may also affect borrowing limits, repayment schedules, fees and cancellation rights.
How Fast Does NotchUp Approve and Fund Advances?
Speed is one of NotchUp’s main advertised advantages.
The company states that its online application is available 24 hours a day, seven days a week, and that eligible applicants may receive funds by Interac e-Transfer in as little as 15 minutes.
However, funding speed can depend on:
- Whether the application is approved.
- Successful completion of income and identity verification.
- Any technical issues with payroll or banking connections.
- Additional checks required by NotchUp.
- Processing times at the receiving financial institution.
Some independent customer reviews report longer delays and technical difficulties. Consequently, borrowers should not rely on the advertised 15-minute timeframe for essential payments with an immediate deadline.
Our online loans guide explains how application decisions and electronic funding differ between lenders.
Is NotchUp Legitimate in Canada?
NotchUp is an identifiable Canadian financial services business operating under the name NotchUp Financial Inc.
Its official website publishes contact information, terms of service and a British Columbia payday-lending licence number.
These details support that NotchUp is an operating business rather than an anonymous lending website.
However, legitimacy should be considered separately from affordability, customer service and regulatory compliance.
NotchUp and Consumer Protection BC
The Better Business Bureau profile for NotchUp references Consumer Protection BC Undertaking Case No. 32086.
According to the Better Business Bureau’s reporting of Consumer Protection BC Undertaking Case No. 32086, the regulator inspected NotchUp’s payday-lending business following an allegation concerning repayment-date requirements for borrowers entering a third or subsequent payday loan agreement within 62 days. Readers should consult the underlying undertaking to understand the findings, commitments and outcome.
This is a matter worth reviewing, but the existence of an undertaking should not be presented as proof of unrelated misconduct.
Consumers can consult the BBB’s NotchUp business profile and the linked Consumer Protection BC documentation for further details.
Before providing banking information, applicants should verify that they are using the genuine website and understand the agreement they are accepting.
NotchUp Reviews and Customer Feedback
Independent customer feedback is an important part of evaluating NotchUp because its promotional messaging emphasizes convenience, quick funding and affordable advances.
NotchUp Trustpilot Reviews
In November 2026, Trustpilot displayed an overall rating of approximately 1.4 out of 5 stars, based on more than 80 reviews.
The feedback reviewed includes recurring complaints about:
- Difficulty reaching customer support.
- Problems connecting or verifying bank accounts.
- Delays between approval and funding.
- Confusion about repayments or optional services.
- Applications being declined after previous advances were repaid.
Some customers also describe positive initial experiences, including straightforward applications and timely transfers.
NotchUp has publicly responded to a number of negative reviews. Customer allegations should be treated as individual experiences rather than independently established facts.
Trustpilot ratings can change and may not represent the experiences of all applicants.
NotchUp Better Business Bureau Profile
The Better Business Bureau lists NotchUp as a non-accredited business and publishes customer complaints and reviews.
Its profile also identifies the Consumer Protection BC undertaking discussed above.
BBB accreditation is voluntary, and the absence of accreditation alone does not establish that a lender is illegitimate. Consumers should consider the nature of complaints, the company’s responses and official regulatory information together.
Our assessment: NotchUp’s independent customer feedback raises meaningful concerns about reliability and communication. Borrowers should weigh these experiences against the company’s advertised features before connecting financial accounts or accepting an advance.
NotchUp Pros and Cons
| Potential Advantages | Potential Disadvantages |
|---|---|
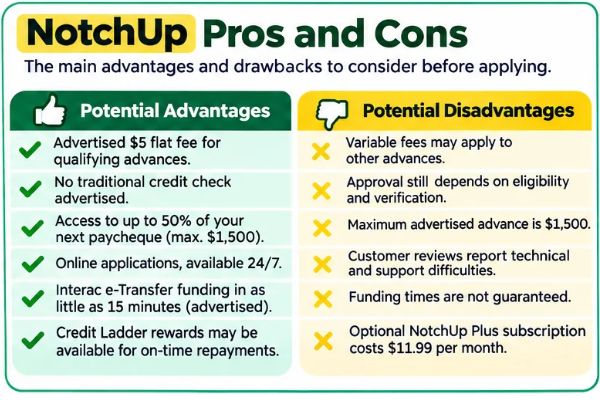
| Advertised $5 flat fee for qualifying payroll-connected advances. | Variable fees may apply to other advances. |
| No traditional credit check advertised. | Approval still depends on eligibility and verification. |
| Access to up to 50% of an expected paycheque, subject to limits. | Maximum advertised advance is $1,500. |
| Online applications available 24/7. | Customer reviews report technical and support difficulties. |
| Interac e-Transfer funding in as little as 15 minutes advertised. | Funding times are not guaranteed. |
| Some government benefit income types may be considered. | Provincial product availability requires confirmation. |
| Optional repayment flexibility through NotchUp Plus. | Plus carries a recurring $11.99 monthly subscription fee. |
| Credit Ladder rewards may be available for on-time repayments. | Late-payment consequences and product-specific fees require careful review. |
NotchUp vs. Traditional Payday Loans
NotchUp’s advertised wage-advance arrangement differs from a conventional payday loan in how the product is marketed and, potentially, how fees are calculated.
However, the company’s legal terms also include payday-lending disclosures, so borrowers should confirm the specific product they are being offered.
| Feature | NotchUp Advertised Wage Advance | Traditional Payday Loan |
|---|---|---|
| Typical amount | Up to 50% of next paycheque, maximum $1,500 | Small, short-term amounts subject to provincial limits |
| Advertised cost | $5 flat fee for qualifying payroll-connected advances; other fees may apply | Borrowing fee based on amount advanced |
| Repayment | Linked to income timing and applicable agreement | Generally short-term, subject to provincial rules |
| Credit check | No traditional credit check advertised | Depends on lender |
| Funding | Fast Interac e-Transfer advertised | Electronic or other methods, depending on lender |
| Main consideration | Confirm actual fees, product type and repayment obligations | High borrowing costs and repayment affordability |
A lower advertised flat fee does not automatically make a product suitable. The full cost, repayment date and risk of repeated borrowing still matter.
Potentially Lower-Cost Alternatives to NotchUp
If you need money before payday, consider whether another option could meet your needs at a lower overall cost.
1. A Personal Loan or Credit Union Loan
For larger borrowing needs, a bank, credit union or alternative lender may offer a longer repayment schedule and a lower annualized cost.
However, minimum loan amounts, credit requirements and fees vary, so compare actual offers carefully.
2. An Existing Line of Credit
If you already have access to a line of credit, borrowing a small amount for a short period may cost less than using repeated advances.
Interest rates and fees still apply. Learn more in our line of credit guide.
3. An Employer Pay Advance
Some employers offer payroll advances directly to employees. Depending on the employer’s policy, this may involve lower fees or no borrowing charge.
Check how an advance affects your next paycheque and whether any administrative costs apply.
4. A Payment Extension
If the money is needed for a bill, contact the provider and ask whether a payment extension or instalment arrangement is available.
This may help avoid taking on additional short-term debt.
5. Compare Other Lending Options
If borrowing remains necessary, compare the costs, eligibility requirements and repayment schedules offered by different providers.
You can explore participating providers through the FatCat Loans Canadian lender network.
FatCat Loans is a loan-matching service, not the lender issuing any resulting loan. Matching does not guarantee approval or a lower borrowing cost.
Important: Repeatedly borrowing against future income can create a cycle in which each paycheque leaves less money available for essential expenses.
Who Might Consider NotchUp — and Who Should Look Elsewhere?
NotchUp May Be Worth Comparing If:
- You need a relatively small advance before your next income payment.
- You can verify eligible income.
- You qualify for the advertised flat-fee arrangement.
- You understand the full repayment amount and due date.
- You can repay without needing another advance immediately afterward.
NotchUp May Be Less Suitable If:
- You need more than $1,500.
- You need long-term financing or predictable monthly instalments.
- You are uncomfortable connecting payroll or banking information.
- You require guaranteed same-day funding.
- You are concerned about the customer-service issues described in independent reviews.
- You cannot comfortably repay the advance from your next income payment.
Borrowers who are already struggling to cover essential expenses should consider seeking financial guidance before taking on additional short-term borrowing.
Frequently Asked Questions About NotchUp Canada
Is NotchUp legitimate in Canada?
NotchUp Financial Inc. is an identifiable Canadian financial services business that publishes a British Columbia payday-lending licence number. However, consumers should independently verify licensing, review applicable agreements and consider customer feedback before applying.
How much does NotchUp charge for an advance?
NotchUp advertises a $5 flat fee for qualifying advances when applicants connect their payroll account. Other advances may carry variable fees, and the company’s published terms include separate payday-loan borrowing disclosures. Always confirm the total fee in your agreement.
Does NotchUp check your credit?
NotchUp advertises no traditional credit checks for its wage-advance service. However, applicants must still meet income, banking and eligibility requirements. Approval is not guaranteed.
How quickly does NotchUp send money?
NotchUp advertises Interac e-Transfer funding in as little as 15 minutes. Actual timing depends on approval, verification, technical processing and the receiving financial institution.
What is the maximum NotchUp advance?
NotchUp advertises advances of up to 50% of your next paycheque, subject to a maximum of $1,500. The actual amount offered depends on eligibility and the company’s assessment.
What is NotchUp Plus?
NotchUp Plus is an optional subscription advertised at $11.99 per month. It offers features such as repayment flexibility, up to four instalments, financial guidance and optional credit reporting. Review the subscription terms before enrolling.
Final Verdict: Is NotchUp Worth Considering in 2026?
NotchUp offers an appealing concept: access to part of your expected income before payday, with no traditional credit check and an advertised $5 flat fee for qualifying advances.
Its online application and potential for fast electronic funding may be convenient for borrowers facing temporary cash-flow shortages.
However, the company’s pricing requires careful attention. The advertised flat fee is not necessarily available to every applicant, additional products and subscription charges exist, and its legal terms contain payday-lending disclosures.
Independent customer reviews also raise concerns about technical reliability, funding delays and customer support.
Our assessment: NotchUp may be worth comparing if you qualify for its advertised flat-fee advance and can comfortably repay on schedule. However, the mixed product disclosures and negative customer feedback make it especially important to verify the exact agreement before applying.
For borrowers who need larger amounts, longer repayment terms or more predictable support, a conventional personal loan or another financing arrangement may be more suitable.
Before borrowing, compare the total repayment, fees, repayment date, cancellation terms and applicable provincial protections.
For further guidance, read our Canadian borrower rights guide.
Sources
- NotchUp – Official Website, Wage Advances and Membership Features
- NotchUp – Terms of Service and Lending Disclosures
- Trustpilot – NotchUp Customer Reviews
- Better Business Bureau – NotchUp Business Profile
- Finder Canada – NotchUp Review
- Financial Consumer Agency of Canada – Payday Loans
Editorial note: This review is based on publicly available information checked in November 2026. FatCat Loans has not independently completed a NotchUp application or obtained a personalized advance offer. Product availability, fees, customer ratings and eligibility requirements may change.
Disclaimer: This article is for general information only and does not constitute financial or legal advice. FatCat Loans is a loan-matching service, not NotchUp or a direct lender. Approval, borrowing costs and funding depend on the provider, applicant and applicable provincial rules. Always review the current agreement before borrowing.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.