Secured vs Unsecured Loans for Bad Credit in Canada: Pros, Cons & Rates
November 04, 2024
Comparing Secured and Unsecured Loans With Bad Credit
Last Updated: September 2026
If you have bad credit and need to borrow money, you may be comparing secured vs unsecured loans for bad credit to understand which option could be more suitable.
The main difference is collateral. A secured loan requires you to pledge an asset, while an unsecured loan doesn’t. Offering collateral may reduce the lender’s risk, but it also means the asset could be at risk if you don’t repay the loan as agreed.
Bad credit can also affect the rates and loan options available to you. An unsecured lender has no specific asset securing the debt, so your credit history, income, existing debts and other eligibility factors may play an important role in the lender’s assessment.
This guide compares secured and unsecured loans for bad credit in Canada, including their pros and cons, borrowing costs, approval considerations and what can happen if you can’t repay.
What Is the Difference Between a Secured and Unsecured Loan?
In Canada, loans are generally categorized based on whether collateral is required:
Secured Loans
A secured loan requires you to provide an asset as collateral. Depending on the type of loan, collateral could include a vehicle, home or another eligible asset.
If you don’t repay the loan according to the agreement, the lender may be able to take the asset used to secure the debt.
Examples of secured borrowing can include:
- secured personal loans
- vehicle loans
- mortgages
- home equity loans and secured lines of credit.
Because collateral can reduce the lender’s financial risk, secured borrowing may sometimes be available at a lower interest rate than comparable unsecured borrowing. However, rates and eligibility still depend on the lender, product and borrower.
Unsecured Loans
An unsecured loan doesn’t require you to pledge an asset as collateral. Instead, the lender assesses whether you meet its lending criteria.
Depending on the lender and product, this may include factors such as your:
- credit history
- income
- existing debts
- employment or income stability
- overall ability to repay.
Unsecured personal loans and some lines of credit are common examples.
Because the lender doesn’t have a specific asset securing the debt, unsecured borrowing may carry a higher interest rate than comparable secured borrowing. Having bad credit can further affect the rate and terms you’re offered, and approval is never guaranteed.
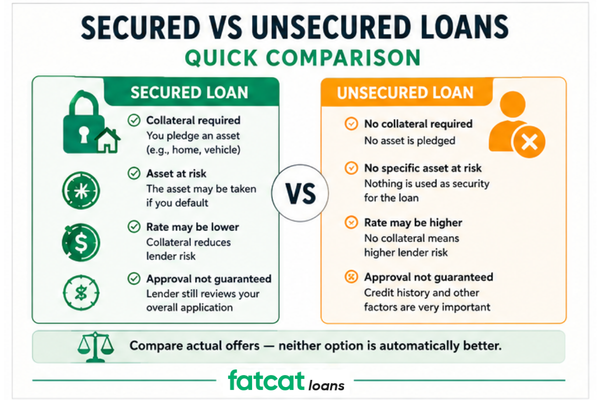
Secured vs Unsecured Loans for Bad Credit: Quick Comparison
Neither type of loan is automatically better if you have bad credit. The important differences are the cost, eligibility requirements and the additional risk you take when using an asset as collateral.
| Feature | Secured Loan | Unsecured Loan |
|---|---|---|
| Collateral | Required | Not required |
| Risk to your property | The pledged asset may be at risk if you default | No specific asset is pledged as collateral |
| Interest rate | May be lower because collateral reduces lender risk | May be higher because there is no collateral |
| Bad credit | Collateral may be considered alongside your credit and overall application | Credit history and other eligibility factors can be particularly important |
| Approval | Not guaranteed | Not guaranteed |
| Access to funds | Timing depends on the lender, product and collateral requirements | Timing depends on the lender and product |
| Default | Lender may be able to take the collateral | Lender may use collections or other legal remedies |
The exact terms depend on the lender and your circumstances. Providing collateral doesn’t guarantee approval, and an unsecured loan isn’t necessarily the more expensive option in every case.
How Does Bad Credit Affect Secured and Unsecured Loans?
Bad credit doesn’t automatically prevent you from getting either a secured or unsecured loan, but it can affect the products, rates and terms available to you.
Lenders can use different criteria when assessing an application. Your credit history may be considered alongside your income, existing debts, ability to make the payments and, for a secured loan, the type and value of the collateral.
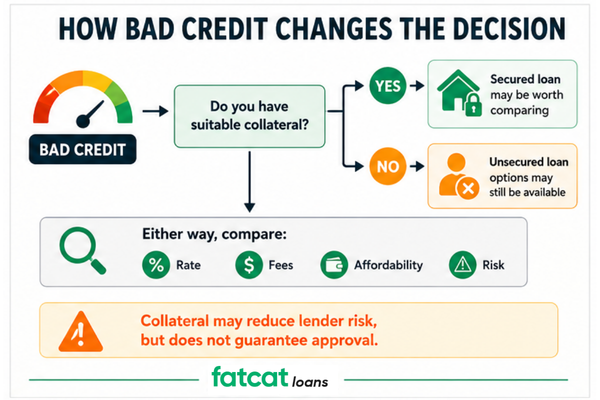
With a secured loan, providing an asset may reduce some of the lender’s risk. However, collateral doesn’t cancel out bad credit or guarantee that your application will be approved.
With an unsecured loan, there is no asset securing the debt. This can make your overall creditworthiness and ability to repay particularly important to the lender.
There is also no single credit score that guarantees approval or rejection across all Canadian lenders. If you’re unsure where your score sits, see our What Counts as a Bad Credit Score in Canada? guide.
Secured vs Unsecured Loan Rates in Canada
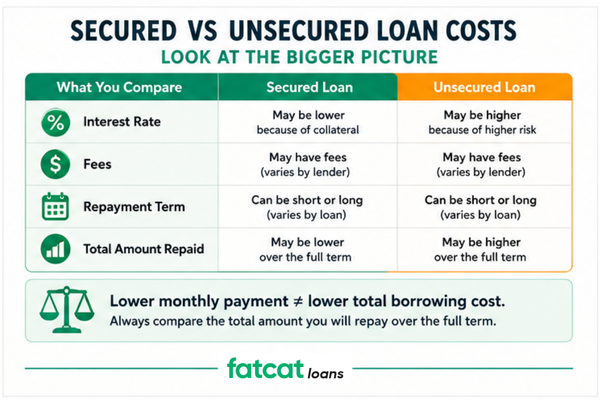
Secured borrowing can sometimes have a lower interest rate than comparable unsecured borrowing because the lender has an asset securing the debt. However, there isn’t one standard secured or unsecured loan rate in Canada.
Your actual rate can depend on the type of loan, lender, credit profile, income, existing debts, term, loan amount and, where applicable, the collateral being offered.
Bank of Canada lending data can help illustrate the difference between some secured and unsecured forms of borrowing. However, these figures are market averages and shouldn’t be treated as rates available to someone with bad credit.
| Chartered Bank Lending Category | Average Interest Rate on Funds Advanced — June 2026 |
|---|---|
| Secured personal lines of credit | 4.05% |
| Unsecured personal lines of credit | 7.69% |
| Personal loan plans | 7.80% |
| Other personal lending | 12.90% |
Source: Bank of Canada, interest rates for new and existing lending by chartered banks, June 2026. These figures are category averages and aren’t advertised rates or predictions of the rate an individual borrower will receive.
Someone with bad credit may be offered a higher rate than these averages, may qualify for a different type of product or may not qualify with a particular lender at all.
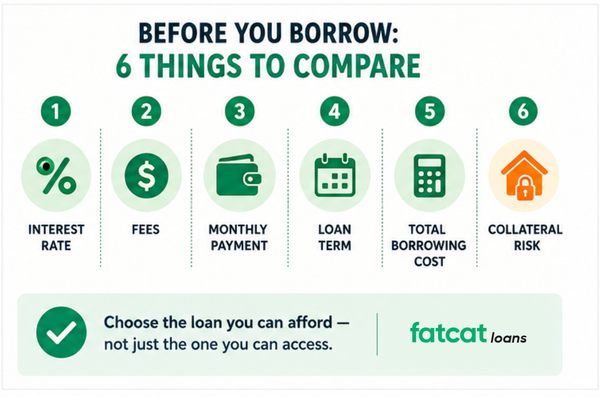
When comparing offers, look beyond the monthly payment. Consider the interest rate, fees, repayment term and total amount you’ll repay.
Pros and Cons of Secured Loans With Bad Credit
Using collateral can change the rates, terms and risks involved when borrowing with bad credit, so it’s important to weigh the potential benefits against the risk of losing the asset.
Potential Benefits
- Potentially lower interest rates: Collateral reduces some of the lender’s risk, which may result in a lower rate than a comparable unsecured loan.
- Different eligibility considerations: The lender may consider the type and value of your collateral alongside your credit history, income, debts and ability to repay.
- Potential access to larger amounts: Some secured products may allow larger loan amounts, although this depends on the lender, product and value of the collateral.
Potential Drawbacks
- Your asset is at risk: If you don’t repay the loan according to the agreement, the lender may be able to take the asset securing the debt.
- Collateral doesn’t guarantee approval: You still need to meet the lender’s eligibility and affordability requirements.
- Additional requirements may apply: Depending on the product, the lender may need to assess the asset or require additional documentation.
- A lower rate doesn’t automatically mean a better loan: Fees, the repayment term and total borrowing cost also matter.
The Financial Consumer Agency of Canada (FCAC) explains that a secured personal loan uses an asset as collateral and that a lender may take the asset if you don’t repay the loan.
Pros and Cons of Unsecured Loans With Bad Credit
An unsecured loan doesn’t put a specific asset at risk as collateral, but qualifying with bad credit may be more difficult or expensive depending on the lender.
Potential Benefits
- No collateral required: You don’t need to pledge your home, vehicle or another eligible asset to secure the loan.
- No specific asset is directly at risk: The lender doesn’t have a pledged asset that it can take simply because the loan is unsecured.
- Different products are available: Unsecured borrowing can include personal loans and some lines of credit, subject to eligibility.
Potential Drawbacks
- Potentially higher borrowing costs: Without collateral reducing the lender’s risk, the interest rate may be higher than on comparable secured borrowing.
- Bad credit can affect your options: Your credit history may influence whether you qualify and the terms you’re offered.
- Approval isn’t guaranteed: Lenders can also consider income, existing debts and your ability to repay.
- Default still has consequences: Not pledging collateral doesn’t mean there are no consequences if you fail to repay the debt.
If you specifically want to borrow without putting up an asset, our Unsecured Loans for Bad Credit in Canada guide explains how these loans work, what lenders may consider and what to check before applying.
Could Collateral Help If You Have Bad Credit?
Offering collateral may influence a lender’s assessment and, in some cases, the rate or terms offered. However, it doesn’t make your credit history irrelevant or guarantee approval.
The lender may still consider factors such as:
- your credit history
- your income
- your existing debts
- your ability to afford the payments
- the type and value of the collateral
- the amount you want to borrow.
The trade-off is important: collateral may reduce risk for the lender, but it increases the potential consequences for you because the pledged asset may be at risk if you default.
Can Secured and Unsecured Loans Affect Your Credit?
Either type of loan may affect your credit history, depending on the lender’s credit-check and reporting practices.
When you apply, the lender may check your credit report as part of its assessment. Before applying, you can ask whether this will involve a hard credit check. You can learn more about the difference in our Soft vs Hard Credit Checks in Canada guide.
If the lender reports your account or payment activity to a credit bureau, making payments as agreed may contribute payment information to your credit history. Late or missed payments that are reported may negatively affect your credit.
Don’t assume every lender reports to both Equifax and TransUnion. If credit reporting is important to you, ask the lender which credit bureau it reports to and what information it reports.
What Happens If You Can’t Repay?
Missing payments can have serious consequences whether your loan is secured or unsecured, but there is an important difference.
If You Can’t Repay a Secured Loan
Because the debt is backed by collateral, the lender may have the right to take the asset securing the loan if you default, subject to the loan agreement and applicable law.
Depending on the product, that could mean putting a vehicle, home or another valuable asset at risk.
Late or missed payments may also affect your credit history if they’re reported to a credit bureau.
If You Can’t Repay an Unsecured Loan
An unsecured lender doesn’t have a specific asset pledged as collateral. However, that doesn’t mean the debt can simply be ignored.
The lender may pursue collection activity or other remedies available under the agreement and applicable law. Missed payments may also affect your credit history if they’re reported.
This is why affordability matters just as much as approval. Before taking either type of loan, make sure the payments fit comfortably within your budget.
Secured vs Unsecured Loans: Which May Suit Your Situation?
There isn’t one loan type that’s best for everyone with bad credit. The decision depends on what you qualify for, the cost of borrowing and whether you’re comfortable putting an asset at risk.
| If This Matters to You… | What to Consider |
|---|---|
| You don’t have suitable collateral | An unsecured loan doesn’t require you to pledge an asset, but eligibility and borrowing costs will depend on the lender and your financial situation. |
| You have an asset you could use as collateral | A secured loan may be an option, but consider whether the potential borrowing benefit is worth putting that asset at risk. |
| You have bad credit | Compare the actual offers you qualify for rather than assuming a secured or unsecured loan will automatically be cheaper or easier to obtain. |
| You receive a lower rate on a secured loan | Compare the total borrowing cost and make sure you’re comfortable with the collateral risk. |
| You need money quickly | Check each lender’s actual application and funding process. Don’t assume every unsecured loan is faster than every secured loan. |
| The payments would stretch your budget | Consider whether borrowing is affordable before accepting either type of loan. |
What to Compare Before Taking Either Loan
Don’t compare loans based only on whether they’re secured or unsecured. Two loans in the same category can have very different costs and terms.
Before accepting an offer, compare:
- Interest rate: the rate charged on the amount you borrow.
- Fees: check for applicable administration, optional-service or other charges included in the agreement.
- Repayment term: a longer term may reduce individual payments but can increase the amount of interest you pay over time.
- Regular payment: make sure the required payment fits your budget.
- Total cost: look at how much you’ll repay over the full term rather than focusing only on the monthly payment.
- Collateral: for a secured loan, understand exactly which asset secures the debt and what could happen if you default.
- Early repayment: check the agreement for any conditions or charges associated with paying the loan off early.
- Credit checks and reporting: ask how the application may affect your credit and whether payment activity is reported to a credit bureau.
The Financial Consumer Agency of Canada recommends comparing factors such as interest rates, fees, payment amounts and the total cost of a personal loan before borrowing.
What If Neither Option Is Affordable?
Getting approved doesn’t necessarily mean taking the loan is the right financial decision.
If the available secured or unsecured loans are too expensive, the payments don’t fit your budget or you’re uncomfortable risking an asset, consider whether you can delay borrowing, reduce the amount you need or explore other options.
If you’re already struggling with existing debts, adding another loan can make your financial position more difficult. You may want to explore free credit counselling in Canada before taking on additional borrowing.
For a broader look at borrowing when your credit is damaged, see our Bad Credit Loans Canada guide.
Frequently Asked Questions About Secured and Unsecured Loans for Bad Credit
Is a secured or unsecured loan better if you have bad credit?
Neither is automatically better. A secured loan requires collateral and may offer different rates or terms because the lender has an asset securing the debt. An unsecured loan doesn’t require collateral but may be more dependent on your creditworthiness and other eligibility factors. Compare the actual cost, terms and risks of any offers you qualify for.
Can I get an unsecured loan with bad credit in Canada?
Possibly. Some lenders consider applicants with lower credit scores, but approval isn’t guaranteed. Your income, existing debts, credit history and ability to repay may also affect the lender’s decision. See our Unsecured Loans for Bad Credit in Canada guide for more information.
Is a secured loan easier to get with bad credit?
Not necessarily. Providing collateral may reduce the lender’s risk, but it doesn’t guarantee approval. The lender may still assess your credit history, income, debts, affordability and the type and value of the asset you’re offering as collateral.
Do secured loans have lower interest rates than unsecured loans?
Secured borrowing may have a lower interest rate than comparable unsecured borrowing because collateral can reduce lender risk. However, your actual rate depends on the lender, product and your financial circumstances, so a secured loan isn’t guaranteed to have the lowest rate available to you.
What happens to my collateral if I can’t repay a secured loan?
If you default on a secured loan, the lender may have the right to take the asset securing the debt, subject to the loan agreement and applicable law. Make sure you understand the consequences before using a home, vehicle or other valuable asset as collateral.
Can secured and unsecured loans affect my credit score?
Potentially. A lender may check your credit when you apply, and account or payment activity may be reported to a credit bureau. If reported, late or missed payments could negatively affect your credit history. Credit-check and reporting practices vary between lenders.
The Bottom Line
If you have bad credit, the choice between a secured and unsecured loan involves more than finding the lowest interest rate.
A secured loan may offer different rates or terms because you’re providing collateral, but that also means putting an asset at risk. An unsecured loan doesn’t require collateral, although your credit history and overall financial situation can have a greater influence on the options available to you.
Before borrowing, compare the interest rate, fees, repayment term, total borrowing cost and monthly payment. If you’re considering a secured loan, also think carefully about whether you’re prepared to risk the asset being used as collateral.
The best option is one you qualify for, understand and can realistically afford to repay — not simply the loan that’s easiest to access.
This article is for informational purposes only and does not constitute financial advice. FatCat Loans is a loan comparison platform, not a lender. We don’t make lending decisions or guarantee approval, rates or terms.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.