Cash Money Review Canada 2026: Loans, Fees & Eligibility
March 23, 2026
Our Review of Cash Money Canada
Last Updated: September 2026
If you’re considering borrowing from Cash Money, this Cash Money review Canada explains how the lender works, the types of credit available, current borrowing costs and what you should check before applying.
Cash Money currently offers Canadians two main online borrowing options:
- Payday Loans of up to $1,500
- Lines of Credit of up to $10,000
Applications are completed online. Cash Money says approved borrowers using Interac e-Transfer may receive funds in as little as 15 minutes, although actual funding times can vary.
Our view: Cash Money offers a quick online application and provides useful information about its borrowing costs. However, payday loans are a high-cost form of credit, while its Line of Credit also carries a relatively high APR. Compare the total cost and repayment structure carefully before borrowing.
If you’d rather compare providers before approaching one lender, you can compare lenders through the FatCat Loans lender network.
Cash Money at a Glance
| Feature | Cash Money |
|---|---|
| Provider | Cash Money |
| Application | Online |
| Payday loan amount | Up to $1,500 |
| Payday loan cost | $14 per $100 borrowed |
| Line of Credit limit | Up to $10,000 |
| Published Line of Credit APR | 34.99% |
| Pre-qualification | Soft credit check |
| Line of Credit acceptance | Hard credit inquiry may apply |
| Funding | As little as 15 minutes with Interac e-Transfer |
| Minimum age | 18+ |
| Income | Steady source of income required |
| Bank account | Open chequing account required |
These details were reviewed in September 2026. Loan availability, amounts and terms can vary according to your province and application, so always check the agreement you’re offered before accepting credit.
What Is Cash Money Canada?
Cash Money is a Canadian lender that says it has served Canadians since 1992.
Its current online borrowing products include:
- payday loans
- Lines of Credit
These products shouldn’t be confused.
A payday loan provides a relatively small amount that is generally repaid around your next payday.
A Line of Credit gives you an approved credit limit. You can draw funds when needed, up to your available limit, and repay the amount through scheduled payments.
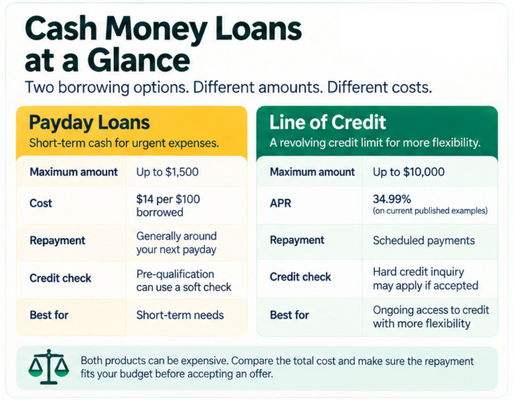
Cash Money currently focuses on online applications. References to in-store borrowing, cheque cashing and money transfers that may appear in older information about Cash Money don’t reflect the products covered in this review.
If you’re looking for broader borrowing options, you can also compare personal loans in Canada through FatCat Loans.
Cash Money Payday Loans
Cash Money currently offers payday loans of up to:
$1,500
Payday loans are short-term loans intended to cover a temporary cash shortage. The amount available depends on your application, income and applicable provincial rules.
Repayment is generally due around your next payday.
Cash Money currently advertises a payday-loan borrowing cost of:
$14 for every $100 borrowed
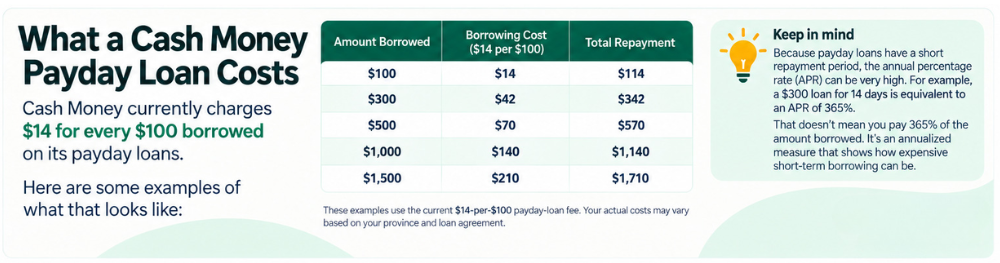
These examples assume a borrowing cost of $14 per $100.
Because repayment periods are short, payday loans can have a very high annualized cost.
For example, Cash Money publishes an example of a $300 payday loan for 14 days with a $42 borrowing cost and total repayment of $342. This is equivalent to an APR of 365%.
That doesn’t mean you pay 365% of the amount borrowed. APR annualizes the short-term borrowing cost, making it easier to understand how expensive the loan is when compared with other forms of credit.
Our guide to how payday loans work in Canada explains these costs in more detail.
Cash Money Payday Loan Rules in Canada
Payday lending is subject to provincial consumer-protection rules.
From January 1, 2025, the maximum permitted payday-loan borrowing cost was reduced to $14 for every $100 borrowed in provinces with approved payday-loan regimes.
The Financial Consumer Agency of Canada (FCAC) also explains that payday-loan rules can cover matters such as:
- maximum borrowing costs
- cancellation rights
- collection practices
- rollover restrictions
- information lenders must disclose
The exact protections depend on your province.
For example, Ontario allows payday-loan borrowers to cancel an agreement within two business days without a penalty or reason. Ontario also prohibits lenders from offering rollover payday loans.
Always check the rules that apply where you live rather than assuming payday-loan protections are identical across Canada.
Cash Money Line of Credit
Cash Money also offers a Line of Credit of up to $10,000.
Unlike a payday loan, a Line of Credit is revolving credit.
You receive an approved credit limit and can draw funds up to your available balance. As you repay borrowed amounts, credit may become available to use again.
Cash Money currently publishes an APR of:
34.99%
for its Line of Credit examples.
Interest is charged on the amount borrowed rather than simply having a fixed payday-loan fee.
Cash Money Payday Loan vs Line of Credit
| Feature | Payday Loan | Line of Credit |
|---|---|---|
| Maximum advertised amount | Up to $1,500 | Up to $10,000 |
| Credit type | Short-term loan | Revolving credit |
| Cost | $14 per $100 borrowed | Interest on amount used |
| Published APR | Very high when annualized | 34.99% |
| Repayment | Generally around next payday | Scheduled payments |
| Repeat borrowing | New loan required | Available credit can be reused |
| Best comparison | Other short-term borrowing | Other Lines of Credit and personal loans |
A Line of Credit may provide more repayment flexibility than a payday loan, but 34.99% APR is still a high borrowing rate.
Our Line of Credit Canada page explains how revolving credit works and what to compare before applying.
Does Cash Money Check Your Credit?
Cash Money says you can check what you may be pre-approved for using a soft credit check, which doesn’t affect your credit score.
The process can be different if you accept a Line of Credit. Cash Money says a hard credit inquiry may then be performed, which can affect your credit score.
Cash Money also considers factors other than your credit score when assessing an application, including income and your ability to repay.
For that reason, we wouldn’t describe Cash Money simply as a “no credit check lender.”
If you’re researching this type of borrowing, our guide to no credit check loans in Canada explains how alternative assessments and credit checks can differ.
Cash Money Eligibility Requirements
Cash Money currently lists basic requirements that include:
- being 18 or older
- having valid identification
- having a steady source of income
- having an open chequing account
- having a working phone number
Requirements and available products can vary by province.
Meeting the basic criteria doesn’t guarantee approval. Cash Money still needs to assess your application before deciding whether to offer credit and how much you can borrow.
If previous credit problems are limiting your choices, you can also compare bad credit loan options in Canada. Compare APRs, fees and total repayment costs carefully.
How to Apply for Cash Money Online
Cash Money’s current application process is online.
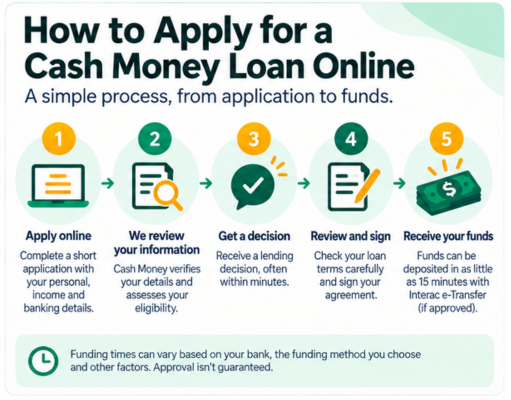
Step 1: Complete the Application
Provide the personal, income and banking information Cash Money requests.
Step 2: Cash Money Reviews Your Application
Cash Money checks your information and assesses your eligibility.
The lender advertises quick decisions, but approval isn’t guaranteed.
Step 3: Review Your Available Offer
If approved, review the product and amount you’ve been offered.
Don’t assume the maximum advertised amount is the amount you’ll qualify for.
Step 4: Read the Agreement
Before accepting an offer, check:
- the amount borrowed
- APR or borrowing fee
- payment amount
- payment dates
- repayment term
- total borrowing cost
- total amount repayable
- consequences of missing a payment
Step 5: Receive Your Funds
Cash Money says approved borrowers may receive funds through methods including Interac e-Transfer and direct deposit.
With Interac e-Transfer, Cash Money advertises funding in as little as 15 minutes. Cash Money also says most applicants receive their funds the same day or within one business day.
Funding times aren’t guaranteed and can depend on the application, funding method, bank processing and other factors.
If you prefer a digital application, you can also compare online loans in Canada before choosing a provider.
Cash Money Pros and Cons
Pros
Online application
The current borrowing process can be completed online.
Fast advertised funding
Cash Money says approved borrowers using Interac e-Transfer may receive funds in as little as 15 minutes.
Published payday-loan costs
The lender clearly publishes its $14-per-$100 payday-loan borrowing cost.
Soft-check pre-qualification
Cash Money says checking what you may be pre-approved for doesn’t affect your credit score.
Two different credit products
Borrowers can consider a short-term payday loan or a larger revolving Line of Credit.
Cons
Payday loans are expensive
A $14 fee for every $100 borrowed becomes very expensive when annualized over a short repayment period.
High Line of Credit APR
Cash Money currently publishes a 34.99% APR for its Line of Credit examples.
Short payday-loan repayment period
Payday loans are generally due around your next payday, which can put pressure on your next paycheque.
Hard credit inquiry may apply
Accepting a Line of Credit can result in a hard credit inquiry.
Fast access doesn’t mean affordable borrowing
A quick application and funding process shouldn’t replace checking whether the repayment fits your budget.
Is Cash Money Legit?
Cash Money is an established Canadian lender that has operated since 1992, according to the company.
Its website publishes information about:
- borrowing costs
- eligibility
- repayment
- provincial payday-loan requirements
- applicable licensing
- credit checks
That provides borrowers with information they can review before accepting an offer.
However, being an established or licensed lender doesn’t mean every loan is affordable or appropriate.
Instead of asking only whether Cash Money is “legit,” consider whether the particular product, borrowing cost and repayment schedule are suitable for your situation.
Cash Money vs Other Loan Options
When comparing Cash Money with other lenders, focus on the actual borrowing costs, repayment terms and eligibility requirements rather than general ratings for features such as speed or flexibility.
Before accepting a Cash Money offer, consider:
- the amount available
- APR or borrowing fee
- repayment period
- payment frequency
- total amount repayable
- credit-check requirements
- missed-payment consequences
- early-repayment rules
If you want to research individual lenders, you can read our GoDay review Canada and iCash review Canada.
Alternatively, you can compare lenders through the FatCat Loans lender network rather than approaching one lender directly.
Alternatives to a Cash Money Payday Loan
Because payday loans are expensive, consider whether a lower-cost option is available first.
Depending on your circumstances, alternatives could include:
-
- an existing bank or credit-union Line of Credit
- a lower-cost personal loan
- an installment loan
- overdraft protection
- asking a service provider about a payment plan
- asking your employer about a pay advance
- using emergency savings
Don’t assume another loan is automatically the best solution.
For example, if you’re having trouble paying several existing debts, adding another loan could make your financial situation harder to manage.
If spreading repayments over time is appropriate, our installment loans in Canada page explains how fixed-payment borrowing works.
What Happens If You Can’t Repay a Cash Money Loan?
The consequences of missing a payment depend on the product and the rules in your province.
For a payday loan, possible consequences can include:
- permitted interest or fees
- NSF charges from your financial institution
- collection activity
- an effect on your credit history
- legal action to recover unpaid debt
Provincial rules limit what payday lenders can charge and how unpaid loans can be collected.
If you think you won’t be able to make a payment, contact Cash Money before the due date and ask what options are available.
Repeatedly borrowing to repay previous loans can make debt harder to manage.
If you’re already struggling with several debts, our Debt Consolidation vs Consumer Proposal vs Bankruptcy in Canada guide explains some of the options available to Canadians experiencing more serious debt problems.
What Should You Check Before Borrowing From Cash Money?
Before accepting an offer, make sure you understand:
- Which product you’re getting
- How much you’re borrowing
- The APR or payday-loan borrowing cost
- How much each payment will be
- When payments are due
- The total amount you’ll repay
- Whether a hard credit inquiry will occur
- What happens if you miss a payment
- Whether early repayment is allowed
- Whether the repayment comfortably fits your budget
Most importantly, don’t choose a loan simply because the application or funding process is fast.
The total cost and your ability to repay matter more than how quickly the money arrives.
Frequently Asked Questions About Cash Money Canada
Is Cash Money Canada legit?
Cash Money is an established Canadian lender that has operated since 1992, according to the company. It publishes information about its loan costs, eligibility requirements and applicable payday-loan rules. However, you should still decide whether the particular product and cost are suitable for you.
How much can I borrow from Cash Money?
Cash Money currently advertises payday loans of up to $1,500 and a Line of Credit of up to $10,000. The amount you’re offered depends on your application, eligibility and province.
How much does a Cash Money payday loan cost?
Cash Money currently advertises a borrowing cost of $14 for every $100 borrowed. At that rate, a $300 payday loan would cost $42, making the total repayment $342.
Does Cash Money check your credit?
Cash Money says checking what you may be pre-approved for uses a soft credit check that doesn’t affect your credit score. A hard credit inquiry may apply if you accept a Line of Credit.
How quickly can I receive money from Cash Money?
Cash Money says most applicants receive their funds the same day or within one business day. Approved borrowers using Interac e-Transfer may receive funds in as little as 15 minutes, although actual funding times can vary.
What happens if I can’t repay a Cash Money loan?
The consequences depend on the product and provincial rules. You may face permitted charges, collection activity or other consequences. Contact Cash Money as early as possible if you think you won’t be able to make a scheduled payment.
Our Verdict: Is Cash Money Worth Considering?
Cash Money provides useful information about its products, including payday-loan costs, eligibility requirements and credit-check practices.
Compared with other payday lenders in Canada, Cash Money’s payday-loan pricing is broadly shaped by provincial regulation, so one of its more notable differences is its established brand recognition.
Its online application and potentially fast funding may also be convenient.
But cost is the main consideration.
Cash Money payday loans cost $14 for every $100 borrowed and have short repayment periods. Its Line of Credit offers access to larger amounts and more flexible borrowing, but its current published APR of 34.99% is still high.
Cash Money may be worth comparing if you understand the full cost, can comfortably afford the repayments and have considered lower-cost alternatives.
It may be less suitable if you’re already struggling with debt or need ongoing financial support.
The decision shouldn’t come down to how quickly Cash Money can provide funds. Compare the total cost, repayment schedule and alternatives before accepting an offer.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.