FlexMoney Loans Review Canada: Rates, Fees & Eligibility
November 13, 2026
Is FlexMoney a Legitimate Lender in Canada?
Last Updated: November 2026
FlexMoney is a Canadian online lending service offering personal instalment loans from $500 to $15,000. Borrowers can apply online and, if approved, repay their loan over a period of 6 to 60 months.
Unlike payday loans, which typically require repayment within a few weeks, FlexMoney offers longer repayment schedules with regular instalments. However, its advertised annual percentage rates (APRs) range from 18.9% to 35%, making it important to compare the total borrowing cost before accepting an offer.
In this FlexMoney loans review Canada, we examine the company’s interest rates, fees, eligibility requirements, application process, funding times and customer feedback.
We’ll also explain how FlexMoney compares with other personal loan options in Canada and what borrowers should consider before applying.
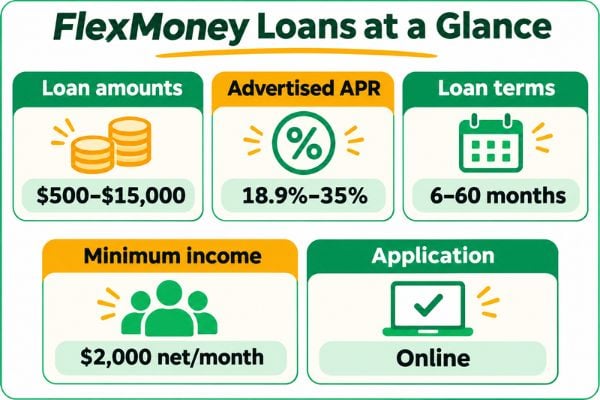
FlexMoney Loans at a Glance
| Feature | Details |
|---|---|
| Lender | FlexMoney |
| Loan type | Unsecured personal instalment loans |
| Loan amounts | $500 to $15,000 |
| Advertised APR | 18.9% to 35% |
| Repayment terms | 6 to 60 months |
| Minimum monthly income | $2,000 net income |
| Minimum age | 20 years |
| Credit checks | Yes |
| Application | Online |
| Funding | Potentially same day or next business day after approval |
| Repayment frequency | Weekly, biweekly, semi-monthly or monthly |
| Application fee | None advertised |
| Origination fee | None advertised |
| Early repayment | Permitted without an advertised prepayment penalty |
| Official website | flexmoney.ca |
Information is based on FlexMoney’s published loan disclosures and eligibility requirements available in November 2026. Rates, terms, availability and approval depend on the applicant and applicable provincial requirements.
How Does FlexMoney Work?
FlexMoney provides online instalment loans that borrowers repay through scheduled payments over an agreed period.
Instead of requiring the entire balance to be repaid on the next payday, the lender spreads repayments across several months or years.
FlexMoney’s online application process generally involves the following steps:
- Choose a loan amount: Request between $500 and $15,000.
- Complete the online application: Provide your personal, income and banking information.
- Verify your identity: Complete any required identity and account verification steps.
- Receive an initial decision: FlexMoney may provide a pre-approval decision within minutes.
- Review the offer: Check the approved amount, APR, repayment schedule and total borrowing cost.
- Sign the agreement: Accept the loan electronically if the terms are suitable.
- Receive funds: Approved loans are deposited into the borrower’s bank account.
An initial pre-approval is not the same as final approval. FlexMoney may complete additional checks before issuing a loan agreement.
FlexMoney Loan Amounts and Repayment Terms
FlexMoney advertises personal instalment loans from $500 to $15,000, with repayment terms ranging from 6 to 60 months.
The amount and term offered depend on the applicant’s income, credit profile, financial circumstances and the lender’s assessment.
FlexMoney offers several repayment schedules:
- Weekly payments.
- Biweekly payments.
- Semi-monthly payments.
- Monthly payments.
Payments are generally collected automatically from the bank account provided during the application.
This flexibility may help borrowers align repayments with their income schedule. However, the repayment frequency does not remove the need to budget for the full loan cost.
Borrowers comparing instalment loans in Canada should consider both the monthly payment and the total amount repayable.
FlexMoney Interest Rates and Fees
FlexMoney advertises annual percentage rates ranging from 18.9% to 35%.
The rate offered to an individual borrower depends on the lender’s assessment of their credit history, credit usage, income and other financial information.
Borrowers with stronger credit profiles may qualify for more favourable rates, while those with weaker credit may receive offers closer to the upper end of the advertised range.

How Much Does a FlexMoney Loan Cost?
To understand the potential borrowing cost, consider a hypothetical $5,000 loan repaid over 24 months.
| Loan Detail | 18.9% Rate | 35% Rate |
|---|---|---|
| Loan amount | $5,000 | $5,000 |
| Repayment term | 24 months | 24 months |
| Estimated monthly payment | $251.80 | $292.59 |
| Estimated total repayment | $6,043.21 | $7,022.23 |
| Estimated total interest | $1,043.21 | $2,022.23 |
Illustrative calculations assume a fixed annual interest rate divided into 12 monthly periods, 24 equal monthly payments and no additional fees. Total figures use unrounded payments. Actual APR calculations, payment schedules and loan offers may differ.
In this example, borrowing at 35% instead of 18.9% increases the estimated interest cost by approximately $979 over two years.
For a useful comparison, request these figures from the lender:
- The total loan principal.
- The annual interest rate and disclosed APR.
- The repayment frequency and amount.
- The number of scheduled payments.
- The total interest payable.
- Any applicable fees or optional charges.
- The total amount repayable over the loan term.
Important: A lower scheduled payment does not automatically mean a cheaper loan. Extending the repayment period can increase total interest, even when the interest rate remains unchanged.
Does FlexMoney Charge Application or Origination Fees?
FlexMoney advertises no application or origination fees.
The lender also states that borrowers can repay their loans early without a prepayment penalty.
These features may reduce certain borrowing costs, particularly for borrowers who are able to repay ahead of schedule.
However, borrowers should review the agreement for any other applicable charges.
What Happens If You Miss a FlexMoney Payment?
Missed payments may result in additional costs and can affect your credit history if the lender reports payment information to a credit bureau.
Returned payments or missed instalments may result in charges where permitted by applicable law. Your bank may also charge an NSF fee. Check FlexMoney’s current agreement for the exact charges and consequences of a missed payment.
If you expect difficulty making a payment, contact the lender before the scheduled withdrawal and ask what arrangements may be available.
Who Can Apply for a FlexMoney Loan?
FlexMoney publishes several basic eligibility requirements.
Applicants generally need to:
- Be at least 20 years old.
- Be a Canadian citizen.
- Receive at least $2,000 in net monthly income.
- Have received qualifying income for at least three months.
- Have an active Canadian bank account with at least three months of banking history.
- Have a valid email address and mobile phone number.
- Meet the lender’s credit and affordability requirements.
- Not be in an active bankruptcy, consumer proposal or credit counselling program.
Meeting these requirements does not guarantee approval.
What Income Does FlexMoney Accept?
According to FlexMoney’s published information, accepted income sources may include:
- Employment income.
- Self-employment income.
- Canada Pension Plan (CPP) payments.
- Old Age Security (OAS) payments.
- Eligible private or public pension income.
The lender states that it does not issue loans based on Employment Insurance, disability benefits, Canada Child Benefit, student aid or certain other government benefits.
Applicants should confirm whether their particular income source qualifies before submitting an application.
Does FlexMoney Accept Bad Credit?
FlexMoney says its lending process considers more than traditional credit bureau information.
However, the company also confirms that it checks applicants’ credit scores when assessing loan applications and determining rates.
This means FlexMoney is not a no-credit-check lender.
Borrowers with fair or weaker credit may still be considered, but approval depends on their overall financial circumstances.
FlexMoney does not clearly publish a universal minimum credit score in the information reviewed. Applicants should not assume that a particular score guarantees approval, as the lender also considers income, existing obligations and other financial information.
If your credit history is less than ideal, explore bad credit loan options in Canada and compare actual borrowing costs before accepting an offer.
Will Applying for FlexMoney Affect Your Credit Score?
FlexMoney confirms that it checks credit scores during its application process.
However, its public information does not clearly establish whether every initial eligibility assessment uses a soft inquiry or whether a hard inquiry occurs at a later stage.
Because hard credit inquiries can affect your credit score, ask FlexMoney which type of inquiry it performs and at what stage before proceeding.
Approval and any future credit-score changes are not guaranteed.
How Fast Does FlexMoney Deposit Money?
FlexMoney advertises fast online processing and direct deposits to Canadian bank accounts.
The company states that many approved borrowers receive their funds on the same day, while others may receive the money on the next business day.
Funding times can depend on:
- When the application is submitted and approved.
- Whether additional verification is required.
- When the signed agreement is received.
- The borrower’s financial institution.
- Banking hours and payment processing schedules.
FlexMoney’s website describes rapid pre-approval, but borrowers should distinguish this from final loan approval and the actual arrival of funds.
Same-day funding is possible, not guaranteed.
Is FlexMoney Available Across Canada?
FlexMoney advertises online instalment lending in multiple Canadian provinces.
Its website describes broad Canadian coverage, although availability remains subject to provincial regulations and lender eligibility rules.
FlexMoney publishes the following high-cost credit licence numbers:
| Province | Published Licence Number |
|---|---|
| British Columbia | 83654 |
| Alberta | 353409 |
These numbers appear in FlexMoney’s published loan disclosures. Their current status has not been independently confirmed through the applicable high-cost credit licensing registers.
Before applying, confirm that FlexMoney currently offers loans in your province and holds any required authorization.
FlexMoney Customer Reviews and Reputation
Independent customer feedback can provide useful insight into the application process, customer service and borrowers’ experiences.
However, individual reviews do not establish whether a lender’s product is suitable or affordable for every applicant.
FlexMoney Trustpilot Reviews
As checked in November 2026, FlexMoney had a Trustpilot rating of approximately 2.4 out of 5, based on six reviews.
Several reviewers reported dissatisfaction with communication, declined applications or the credit-check process.
However, six reviews represent a very small sample. The rating should not be treated as a reliable measure of every customer’s experience.
Review scores and counts can change. See the FlexMoney Trustpilot profile for the latest feedback.
FlexMoney Reviews on Finder Canada
Finder Canada’s FlexMoney review displays a separate customer rating of approximately 3.8 out of 5, based on 20 reviews.
Some customers describe a straightforward application and helpful service, while others report confusion during the process or dissatisfaction with lending decisions.
Finder’s customer rating and Trustpilot’s rating come from different groups of reviewers and should not be combined into a single score.
Is FlexMoney a Legitimate Canadian Lender?
FlexMoney operates an established Canadian lending website and publishes information about its loan products, fees, eligibility requirements and provincial high-cost credit licences.
Its published information also identifies a Toronto business location and customer support contact details.
These are useful indicators when researching a lender. However, borrowers should still independently verify the applicable licensing information and read the complete loan agreement.
Being an established lender does not automatically mean a loan is affordable or appropriate for every borrower.
FlexMoney Pros and Cons
Advantages
- Loan amounts from $500 to $15,000.
- Repayment terms ranging from 6 to 60 months.
- Fully online application process.
- Potentially fast funding after approval.
- No advertised application or origination fees.
- No advertised early repayment penalty.
- Several repayment frequencies.
- Some pension and self-employment income may qualify.
Disadvantages
- Advertised APRs can reach 35%.
- Credit checks are part of the application process.
- A minimum of $2,000 in net monthly income is required.
- Applicants must meet the lender’s minimum age and citizenship requirements.
- Not all income sources qualify.
- Active bankruptcy, consumer proposal or credit counselling participation can prevent eligibility.
- Longer repayment terms may increase total interest.
- Customer feedback is mixed, with limited Trustpilot review volume.

FlexMoney vs. Traditional Bank Personal Loans
| Feature | FlexMoney | Traditional Bank Personal Loan |
|---|---|---|
| Loan amounts | $500 to $15,000 | Varies by bank |
| APR | 18.9% to 35% advertised | Varies by bank and applicant |
| Repayment term | 6 to 60 months | Varies by product |
| Application | Online | Online, telephone or branch options may be available |
| Credit assessment | Credit check and financial assessment | Credit check and financial assessment |
| Funding | Potentially same day or next business day | Depends on the bank and approval process |
| Fees | No advertised application or origination fees | Varies by bank and product |
FlexMoney may appeal to borrowers who prefer a fully online process or who do not qualify for their preferred bank loan.
However, borrowers with strong credit may be able to obtain lower borrowing rates elsewhere.
Always compare actual loan offers rather than assuming one lender category is automatically cheaper.
Alternatives to FlexMoney Loans
Before applying for a FlexMoney loan, consider whether another borrowing option could better suit your financial circumstances.
1. Traditional Personal Loans
Banks, credit unions and other lenders offer unsecured personal loans with different interest rates, terms and eligibility requirements.
Borrowers with stronger credit may qualify for more competitive rates, although approval is not guaranteed.
2. Other Online Instalment Lenders
Online lenders may offer different loan amounts, repayment schedules and credit requirements.
Compare the disclosed APR, fees and total repayment amount rather than focusing only on approval speed.
3. Personal Lines of Credit
A personal line of credit may offer flexible borrowing and potentially lower interest rates for eligible applicants.
However, variable rates and minimum-payment structures can make repayment costs less predictable.
4. Debt Consolidation Loans
If you are borrowing primarily to repay existing credit card balances, consider whether a debt consolidation loan would reduce your total borrowing costs.
Consolidation is only financially beneficial when the repayment terms, interest and fees make sense for your situation.
5. Compare Multiple Lenders
Instead of relying on a single provider, you can explore participating lenders through the FatCat Loans Canadian lender network.
FatCat Loans is a loan-matching service, not a direct lender. Available products, eligibility requirements and approval decisions depend on participating providers.
Who Might Consider FlexMoney?
FlexMoney may be worth comparing for borrowers who:
- Need between $500 and $15,000.
- Prefer a fully online application.
- Have at least $2,000 in qualifying monthly net income.
- Want predictable scheduled instalment payments.
- Understand the interest rate and full repayment cost.
- Can comfortably afford the payments without missing essential expenses.
It may be less suitable for borrowers who need a lower interest rate, do not meet the income requirements or are already struggling to repay existing debts.
Borrowers who are considering another loan to cover regular living expenses should review their budget and consider independent financial guidance before taking on additional debt.
Frequently Asked Questions About FlexMoney Loans
Is FlexMoney a legitimate lender in Canada?
FlexMoney is an established Canadian online lending service offering personal instalment loans. It publishes loan disclosures and provincial high-cost credit licence numbers. Borrowers should verify current licensing and loan availability before applying.
How much can I borrow from FlexMoney?
FlexMoney advertises personal loans from $500 to $15,000. The amount offered depends on the applicant’s income, credit profile and other eligibility requirements.
What interest rates does FlexMoney charge?
FlexMoney advertises APRs ranging from 18.9% to 35%. Your actual rate depends on the lender’s assessment and will be disclosed in your loan offer.
Does FlexMoney accept bad credit?
FlexMoney says it considers different credit profiles, including some borrowers with weaker credit. However, it performs credit checks, and approval is not guaranteed.
Does FlexMoney perform a hard credit check?
FlexMoney confirms that it checks applicants’ credit scores, but its public information does not clearly explain whether every initial assessment involves a soft or hard inquiry. Ask the lender before proceeding if you are concerned about the impact on your credit score.
How quickly does FlexMoney deposit funds?
FlexMoney says many approved borrowers receive their funds on the same day or next business day. Actual funding times depend on verification, approval timing and bank processing.
What income do I need for a FlexMoney loan?
FlexMoney generally requires at least $2,000 in qualifying net monthly income for a minimum of three months. Employment, self-employment and certain pension income may qualify.
Can I repay a FlexMoney loan early?
FlexMoney advertises early repayment without a prepayment penalty. Check your agreement to confirm how early repayment affects your remaining interest and total borrowing cost.
Does FlexMoney charge an application fee?
FlexMoney advertises no application or origination fees. Other charges may apply in certain circumstances, so review the complete loan agreement before signing.
Final Verdict: Is FlexMoney Worth Considering?
FlexMoney offers online instalment loans with flexible repayment schedules, advertised APRs from 18.9% to 35%, and loan amounts of $500 to $15,000.
Its main advantages include a straightforward online application, several repayment options, no advertised origination fees and the possibility of receiving funds quickly after approval.
However, the interest rates can be expensive, especially for borrowers who receive offers near the upper end of the advertised range.
FlexMoney also performs credit checks and has income and eligibility requirements that may exclude some applicants.
For borrowers who can qualify for lower-cost credit, comparing bank loans, credit union products and other online lenders may lead to a more affordable option.
Our verdict: FlexMoney is worth comparing if you need an instalment loan and meet its requirements, but it should not automatically be your first choice without checking competing offers and total repayment costs.
Ready to Compare Canadian Loan Options?
Before accepting a loan, compare available rates, repayment terms and total borrowing costs.

Loan approval, rates, amounts and terms depend on participating lenders and individual eligibility.
Sources and Further Reading
- FlexMoney – Official Loan Products and Disclosures
- FlexMoney – Eligibility, Application and FAQs
- Finder Canada – FlexMoney Personal Loan Review
- Trustpilot – FlexMoney Customer Reviews
- Financial Consumer Agency of Canada – Personal Loans
Editorial disclosure: This review is based on publicly available lender disclosures, independent reviews and consumer information. FatCat Loans is not FlexMoney and does not determine its lending decisions. Loan products, eligibility requirements, rates, fees, licensing and customer ratings may change. Readers should verify current details before applying.
Financial disclosure: This article provides general educational information and is not personalized financial advice. Review all borrowing costs and repayment obligations before accepting any loan.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.