Mr. Payday Loans Canada Review: Rates, Fees & Eligibility
November 09, 2026
Is Mr. Payday a Legitimate Lender in Canada?
Last Updated: November 2026
Mr. Payday is a Canadian short-term loan provider offering online payday loans to eligible borrowers in British Columbia, Alberta and Ontario. The company advertises loans from $100 to $1,500, with a borrowing fee of $14 per $100.
Mr. Payday may appeal to borrowers who need a relatively small amount of money and want a straightforward online application. However, payday loans are an expensive form of borrowing, particularly when compared with conventional personal loans or lines of credit.
In this Mr. Payday Loans review Canada 2026, we examine the company’s loan amounts, fees, eligibility requirements, repayment terms, funding speed, customer feedback and potential drawbacks.
We’ll also explain when a lower-cost borrowing alternative may be more appropriate.
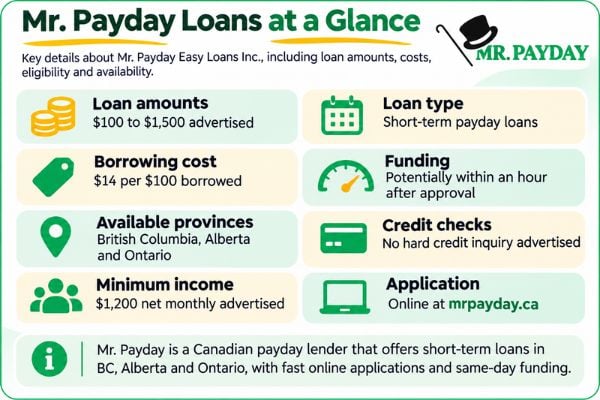
Mr. Payday Loans at a Glance
| Feature | Details |
|---|---|
| Company | Mr. Payday Easy Loans Inc. |
| Loan type | Short-term payday loans |
| Loan amounts | $100 to $1,500 advertised |
| Borrowing cost | $14 per $100 borrowed |
| Available provinces | British Columbia, Alberta and Ontario |
| Repayment terms | Short-term, subject to provincial rules and the loan agreement |
| Credit checks | No hard credit inquiry advertised |
| Minimum income | $1,200 net monthly advertised |
| Funding | Potentially within an hour after approval |
| Application | Online |
| Official website | mrpayday.ca |
Information is based on published lender disclosures and third-party reporting available in November 2026. Loan availability, eligibility, terms and funding times may change. Always confirm the details in your agreement.
How Does Mr. Payday Work?
Mr. Payday provides short-term loans intended to be repaid over a relatively brief period.
Unlike a traditional personal loan, which may allow repayments over several months or years, a payday loan typically has a much shorter repayment schedule.
The general process involves:
- Submitting an online application.
- Providing personal, income and banking information.
- Allowing the lender to verify your eligibility and repayment capacity.
- Reviewing the borrowing fee and repayment agreement.
- Accepting the agreement if the terms are suitable.
- Receiving funds if approved and successfully processed.
- Repaying the amount borrowed plus applicable charges on the agreed date or dates.
Mr. Payday describes itself as a direct lender. This means it handles its own lending process rather than simply referring applicants to unrelated lenders.
However, being a direct lender does not automatically make a payday loan affordable or suitable for every borrower.
Mr. Payday Loan Amounts and Repayment Terms
Mr. Payday advertises payday loans ranging from $100 to $1,500.
The amount offered depends on the applicant’s financial circumstances, provincial lending requirements and the lender’s assessment.
Repayment periods also depend on the province.
- British Columbia: Short-term repayment arrangements subject to provincial payday lending rules.
- Alberta: Payday loans must have a term of at least 42 days.
- Ontario: Short-term repayment arrangements subject to Ontario payday lending rules.
Payday loans generally have terms of no more than 62 days. In Alberta, the minimum term is 42 days, so borrowers should not assume that a 14-day repayment example applies in every province.
Borrowers should confirm the exact due dates, payment amounts and total borrowing cost before accepting an offer.
Mr. Payday Interest Rates and Fees
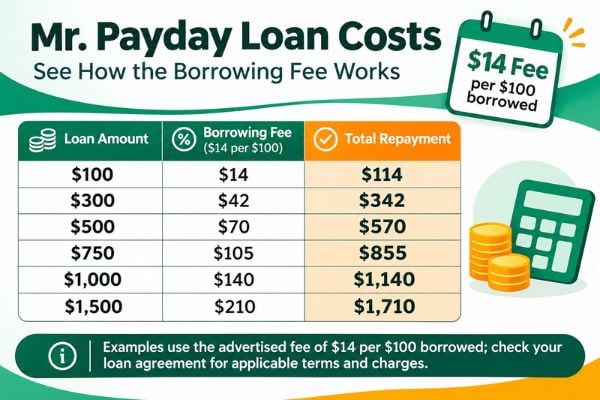
Mr. Payday advertises a borrowing cost of $14 for every $100 borrowed.
This means a $500 loan would carry a $70 borrowing fee, assuming the advertised rate applies and no additional permitted charges arise.
Mr. Payday Loan Cost Examples
| Loan Amount | Borrowing Fee | Total Repayment |
|---|---|---|
| $100 | $14 | $114 |
| $300 | $42 | $342 |
| $500 | $70 | $570 |
| $750 | $105 | $855 |
| $1,000 | $140 | $1,140 |
| $1,500 | $210 | $1,710 |
Illustrative calculations based on a fee of $14 per $100 borrowed. Actual loan availability and permitted charges depend on provincial rules and the agreement.
What Is the APR on a Mr. Payday Loan?
Payday loan fees can appear relatively small in dollar terms, but the cost becomes substantial when expressed as an annualized percentage.
For example, borrowing $500 for 14 days with a $70 fee produces an approximate simple annualized cost of:
($70 ÷ $500) × (365 ÷ 14) × 100 = 365% per year
This 365% figure illustrates the annualized cost of borrowing, not the amount charged for this 14-day loan. In this example, the borrowing fee remains $70, making the total repayment $570.
The precise APR disclosed under applicable provincial rules may use different calculation conventions. Always rely on the required APR and total cost disclosures in the actual loan agreement.
Mr. Payday’s published materials also include an Ontario disclosure showing an APR of 391.07% for a $500 loan over 14 days. This differs from the simple annualized calculation above, so borrowers should check the province-specific APR disclosed in their agreement.
A longer repayment period changes the annualized percentage even when the dollar borrowing fee is unchanged.
For this reason, comparing the fee alone with a conventional personal loan’s annual interest rate can be misleading.
Are There Additional Fees?
Mr. Payday advertises no application fees and no prepayment penalties.
However, missed payments may result in additional charges or interest where permitted by provincial law. Your bank may also charge a fee if a scheduled payment is returned for insufficient funds.
Check the lender’s official rates and fees page and your specific agreement before borrowing.
Who Can Apply for a Mr. Payday Loan?
Mr. Payday advertises the following general eligibility requirements:
- Residence in British Columbia, Alberta or Ontario.
- Meeting the applicable minimum legal age.
- Net monthly income of at least $1,200.
- An active chequing account.
- A working telephone number.
- Verifiable income that meets the lender’s requirements.
Mr. Payday’s published information indicates a minimum age of 19 in British Columbia and 18 in Alberta and Ontario.
The company says it considers several income sources, including employment, certain pension payments and eligible government benefits.
However, acceptance of a particular income source does not guarantee loan approval.
Does Mr. Payday Accept Bad Credit?
Mr. Payday advertises a lending process that does not rely on a traditional hard credit inquiry.
Instead, the lender says it considers income and banking information when assessing applications.
This may make its products accessible to some borrowers who have difficulty qualifying for conventional credit.
However, no hard credit check does not mean guaranteed approval.
Applicants may still be declined because of insufficient income, existing obligations, banking history or other eligibility concerns.
If you have a lower credit score, you can also explore bad credit loan options in Canada and compare the total borrowing costs before deciding.
How Fast Does Mr. Payday Deposit Money?
Mr. Payday promotes fast online processing and funding through Interac e-Transfer.
Its published information and third-party reviews indicate that some approved applicants may receive funds within approximately 30 to 60 minutes.
However, funding speed is not guaranteed.
Processing times can depend on application verification, lender business hours, banking arrangements and other factors.
Borrowers should not assume that every application will be approved or funded immediately.
Mr. Payday Customer Reviews and Reputation
Customer feedback can provide useful information about the application experience, customer service and processing times.
However, reviews cannot establish whether a loan is affordable for your particular circumstances.
Trustpilot Reviews
As checked in November 2026, Mr. Payday Easy Loans Inc. had a Trustpilot rating of approximately 4.7 out of 5, based on around 1,800 reviews.
Positive reviewers frequently mention:
- Fast application processing.
- Helpful customer service.
- Convenient online applications.
- Quick access to funds after approval.
Some negative reviewers report declined applications, unexpected delays or dissatisfaction with communication.
These are customer-reported experiences, not independently verified outcomes.
Review scores change over time. You can check the latest feedback on Mr. Payday’s Trustpilot profile.
Is Mr. Payday Licensed in Canada?
Mr. Payday publishes the following provincial licence numbers:
| Province | Published Licence Number |
|---|---|
| British Columbia | 50031 |
| Alberta | 326997 |
| Ontario | 4716300 |

These numbers are published on the lender’s official website. Borrowers should independently confirm the current licence status with the appropriate provincial regulator before applying.
A lender’s licensing information is an important legitimacy check, but it does not eliminate the financial risks of high-cost borrowing.
Mr. Payday Pros and Cons
Advantages
- Online application process.
- Small loan amounts starting at $100.
- Advertised funding within a short period after approval.
- No hard credit inquiry advertised.
- Several types of verifiable income may be considered.
- Published borrowing fees and provincial licence information.
Disadvantages
- Very high annualized borrowing costs.
- Short repayment periods can create budget pressure.
- Availability is limited to three provinces.
- Maximum advertised loan amount is $1,500.
- Approval and funding times are not guaranteed.
- Missed payments can result in additional costs.
- Repeated payday borrowing can contribute to ongoing financial difficulties.
Mr. Payday vs. a Traditional Personal Loan
| Feature | Mr. Payday | Traditional Personal Loan |
|---|---|---|
| Loan purpose | Small, short-term borrowing | Various personal expenses |
| Loan amount | $100–$1,500 advertised | Varies by lender |
| Repayment period | Short-term | Often several months or years |
| Borrowing cost | High-cost payday loan fee | Interest and possible fees |
| Credit assessment | No hard inquiry advertised | Varies; hard inquiries are common |
| Availability | BC, AB and ON | Depends on lender and province |
A personal loan in Canada may provide a longer repayment period and potentially lower borrowing costs, depending on the lender and applicant.
However, a longer repayment period can also increase total interest. Always compare the full repayment amount.
Alternatives to Mr. Payday Loans
Before taking out a high-cost payday loan, consider whether a lower-cost option could meet your needs.
1. Personal Loans
Some personal lenders offer smaller unsecured loans with instalment repayments. Rates, fees and eligibility vary considerably.
2. Lines of Credit
A line of credit may offer more flexible access to funds and potentially lower interest costs for qualified borrowers.
3. Payment Arrangements
If you need money to cover an upcoming bill, ask the service provider whether a payment extension or instalment arrangement is available.
4. Employer Salary Advances
Some employers may offer salary advances or emergency assistance. Check the terms and any applicable fees.
5. Credit Counselling
If short-term borrowing has become a regular necessity, a reputable credit counselling agency may help you review your budget and explore alternatives.
You can also compare available providers through the FatCat Loans Canadian lender network.
FatCat Loans is a loan-matching service, not a direct lender. Its participating lenders may offer different loan products, and approval is not guaranteed.
Who Might Consider Mr. Payday?
Mr. Payday may be considered by an eligible borrower who:
- Needs a relatively small amount for a short-term expense.
- Has confirmed that lower-cost options are unavailable or unsuitable.
- Understands the full borrowing fee and repayment terms.
- Can repay the loan without sacrificing essential expenses.
- Does not expect to need another payday loan immediately afterward.
It is generally less suitable for people who are already unable to cover regular living costs, need longer-term financing or are relying on repeated payday borrowing to meet existing obligations.
Frequently Asked Questions About Mr. Payday Loans
Is Mr. Payday a legitimate lender in Canada?
Mr. Payday Easy Loans Inc. is an established Canadian payday loan company that publishes licence numbers for British Columbia, Alberta and Ontario. Borrowers should verify the current licence status with their provincial regulator before applying.
How much can I borrow from Mr. Payday?
Mr. Payday advertises loans from $100 to $1,500. The amount available depends on eligibility, provincial requirements and the lender’s assessment.
How much does a $500 Mr. Payday loan cost?
At the advertised fee of $14 per $100 borrowed, a $500 loan costs $70 in borrowing fees, making the total repayment $570, assuming no additional applicable charges.
Does Mr. Payday check your credit score?
Mr. Payday says it does not perform a hard credit inquiry that would affect your Equifax or TransUnion credit score. However, it still assesses income, banking information and other eligibility factors.
How quickly does Mr. Payday approve loans?
Mr. Payday advertises fast application processing, with some approved borrowers potentially receiving funds within approximately 30 to 60 minutes. Actual approval and funding times vary.
Can I apply for Mr. Payday with bad credit?
Mr. Payday considers applications without relying on a traditional hard credit inquiry, but bad credit approval is not guaranteed. Income, banking history and affordability requirements still apply.
Which provinces does Mr. Payday serve?
Mr. Payday advertises payday lending services in British Columbia, Alberta and Ontario.
Can I repay a Mr. Payday loan early?
Mr. Payday says borrowers can repay early without a prepayment penalty. Check your agreement and applicable provincial rules to understand whether any borrowing-cost refund applies.
Final Verdict: Is Mr. Payday Worth Considering?
Mr. Payday is an established Canadian payday lender offering small, short-term loans in British Columbia, Alberta and Ontario.
Its main advantages are its online application, published fees, potential for fast funding and willingness to assess some applicants without a traditional hard credit inquiry.
However, its loans are expensive. A $500 loan with a $70 fee represents a substantial cost for borrowing over a short period.
For borrowers who can qualify for lower-cost credit, a personal loan, line of credit or payment arrangement may be a more affordable solution.
Mr. Payday should not be viewed as a long-term debt management strategy.
Compare Other Canadian Loan Options
Before committing to a high-cost payday loan, compare the total borrowing costs and repayment terms of other available options.

Loan approval, rates, amounts and terms depend on participating lenders.
Sources and Further Reading
- Mr. Payday – Official Rates and Fees
- Mr. Payday – Contact and Published Licensing Details
- Finder Canada – Mr. Payday Review
- Trustpilot – Mr. Payday Customer Reviews
- Financial Consumer Agency of Canada – Payday Loans
Editorial disclosure: This review is based on publicly available lender information, third-party reporting and consumer guidance. FatCat Loans is not Mr. Payday and does not determine its lending decisions. Rates, terms, eligibility, licensing and customer review scores may change. Readers should verify all relevant details before applying.
Financial disclosure: This article is for general information and does not constitute personalized financial advice. Payday loans are high-cost products. Consider lower-cost alternatives and your ability to repay before borrowing.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.