Credit Club Canada Review 2026: Rates, Fees, Eligibility & Pros and Cons
November 06, 2026
Is Credit Club a Good Payday Loan Option in Canada?
Last Updated: November 2026
In this Credit Club Canada review 2026, we examine the lender’s borrowing costs, eligibility requirements, application process, customer reviews, provincial availability and alternatives.
Credit Club is a Canadian short-term lender offering online payday loans to eligible borrowers in Ontario, British Columbia and Nova Scotia. The company advertises loans of up to $1,500, no traditional credit checks and fast electronic funding.
Its published borrowing fee is $14 for every $100 borrowed. That means a $500 payday loan would cost $70 in borrowing fees, bringing the total repayment to $570.
Credit Club also has a substantial independent review history, with a strong Trustpilot rating and BBB accreditation. However, payday loans remain expensive forms of short-term borrowing, even when a lender receives favourable customer feedback.
Before applying, consider whether a personal loan in Canada or another borrowing option could meet your needs at a lower overall cost.
Credit Club Canada: Quick Overview
| Feature | Credit Club Details |
|---|---|
| Company | Credit Club, operated by Club Credit Inc. / Credit Club Incorporated |
| Official website | creditclubloans.com |
| Established | 2012, according to the company |
| Loan type | Online payday and short-term loans |
| Advertised loan range | Up to $1,500; new customers may qualify for up to $500 |
| Borrowing fee | $14 per $100 borrowed |
| Illustrative APR | Approximately 365% for a 14-day loan at the advertised fee |
| Repayment | Normally due on the next payday or around 14 days after funding; actual terms may vary |
| Credit check | No traditional credit check advertised |
| Funding | Electronic transfer, potentially the same business day |
| Provinces served | Ontario, British Columbia and Nova Scotia |
| Minimum age | 18 or older, subject to provincial age requirements |
| Missed payment charges | NSF or default charges may apply, subject to the loan agreement and provincial law |
| Trustpilot | Approximately 4.8/5 from over 3,700 reviews in November 2026 |
| BBB | A+ rating and accredited business at time of review |
Information is based on Credit Club’s published website, pricing and FAQs, together with independent review platforms. Actual loan terms depend on eligibility, the agreement and provincial requirements.
What Is Credit Club and How Does It Work?
Credit Club is an online Canadian lender that provides small, short-term loans to help eligible borrowers cover expenses before their next payday.
According to the company, it has operated since 2012 and focuses on a straightforward digital application process, transparent borrowing fees and customer service.
Although some of its website content describes its products as personal loans, its regulatory disclosures and repayment structure identify its core offering as payday lending.
This distinction matters because a payday loan typically has a much shorter repayment period and a higher annualized borrowing cost than a conventional instalment-based personal loan.

How to Apply for a Credit Club Loan
- Complete the online application: Provide your personal details, contact information, employment details and requested loan amount.
- Verify your banking information: Credit Club may request electronic banking verification to assess income and repayment eligibility.
- Wait for a decision: The company advertises decisions within approximately one hour of completing banking verification during business hours.
- Review the loan agreement: Check the borrowing fee, total repayment, due date and missed-payment conditions.
- Accept the offer: If approved and satisfied with the terms, complete the agreement.
- Receive your funds: Credit Club arranges electronic funding, with same-business-day delivery possible in some cases.
Approval and funding times are not guaranteed. Applications submitted outside business hours or requiring additional checks may take longer.
How Much Can You Borrow From Credit Club?
Credit Club advertises loans of up to $1,500, but the amount available depends on the applicant’s circumstances.
Its official FAQ states that new customers may qualify for up to $500. Other promotional pages discuss loan amounts up to $1,500.
These figures should not be interpreted as guaranteed limits for every borrower.
Credit Club may consider your employment history, regular income, banking information and ability to repay when determining an offer.
For example, a first-time applicant requesting $1,000 may be offered a smaller amount or declined, even if they meet the basic eligibility requirements.
Credit Club Interest Rates and Fees Explained
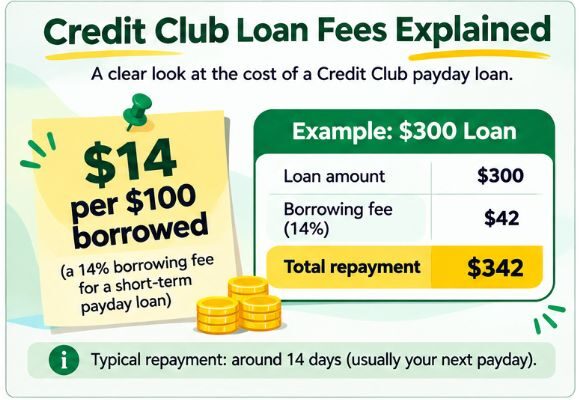
Credit Club advertises a borrowing fee of $14 per $100 borrowed.
Unlike a conventional personal loan that charges interest over several months or years, a typical payday loan charges a fee for borrowing money over a short period.
How Much Does a Credit Club Loan Cost?
| Loan Amount | Borrowing Fee | Total Repayment |
|---|---|---|
| $100 | $14 | $114 |
| $200 | $28 | $228 |
| $300 | $42 | $342 |
| $500 | $70 | $570 |
| $750 | $105 | $855 |
| $1,000 | $140 | $1,140 |
| $1,500 | $210 | $1,710 |
Illustrative calculations based on Credit Club’s advertised $14-per-$100 fee. They do not confirm eligibility for every amount and exclude charges arising from missed payments.
For example, borrowing $300 would result in a $42 fee and a total repayment of $342.
Credit Club’s published pricing describes this fee structure as applying to its short-term loans. Always check the actual agreement for the full repayment amount and due date.
What Is Credit Club’s APR?
Credit Club’s provincial disclosures illustrate an annual percentage rate of approximately 365% for a 14-day payday loan charging $14 per $100 borrowed.
The annualized figure is high because a 14% fee is charged over a very short period.
For example, a $300 loan with a $42 fee over 14 days produces a simple annualized borrowing cost of approximately 365%.
This does not mean that a borrower necessarily pays 365% of the principal on a single 14-day loan. The actual fee in this example is $42.
However, the APR helps illustrate why payday borrowing is expensive compared with many longer-term credit products.
What Happens If You Miss a Payment?
If a scheduled repayment fails, Credit Club may charge an NSF or default fee, subject to the applicable provincial rules and loan agreement. Its published Nova Scotia disclosure refers to a maximum default penalty of $20 per loan. Your financial institution may also charge a separate returned-payment fee.
Its published terms also describe annualized default interest of 30% on overdue balances and warn that non-payment may lead to collection activity or negatively affect a borrower’s credit history.
Your bank may separately charge an overdraft or returned-payment fee.
Because default charges are regulated provincially, review the terms applicable to your province rather than assuming every charge applies in the same way throughout Canada.
Credit Club states that it does not offer automatic payday-loan renewals.
Who Qualifies for a Credit Club Payday Loan?
Credit Club’s official FAQ lists several basic eligibility requirements.
- Be at least 18 years old, subject to provincial age-of-majority requirements.
- Live in Ontario, British Columbia or Nova Scotia.
- Have an active bank account.
- Be employed by the same employer for more than three months.
- Provide the personal and banking information needed for verification.
Meeting these requirements does not guarantee approval.
The company may consider additional factors, including income stability and repayment affordability.
Does Credit Club Perform a Credit Check?
Credit Club advertises no traditional credit check as part of its application process.
Instead, the company describes using income and banking information to assess applicants.
This may make Credit Club worth comparing for borrowers with limited or damaged credit histories, but it does not mean every applicant will qualify.
For more information, see our no credit check loans guide and bad credit loans in Canada.
Which Provinces Does Credit Club Serve?
Credit Club advertises payday-lending services in three Canadian provinces:
- Ontario: Including Toronto, Ottawa, Hamilton, Mississauga and other eligible locations.
- British Columbia: Including Vancouver, Victoria, Surrey and other eligible locations.
- Nova Scotia: Including Halifax, Dartmouth and other eligible locations.
Its published licence numbers are:
| Province | Published Licence Number |
|---|---|
| Ontario | 4726568 |
| British Columbia | 64068 |
| Nova Scotia | 262985929 |
These numbers are published by Credit Club. Applicants should verify current licence status directly with the relevant provincial regulator before borrowing.
Important licensing note: The Ontario licence certificate linked from Credit Club’s website shows an expiry date of September 7, 2026. A current renewal was not independently confirmed during this review. An expired published certificate does not, by itself, establish that the company is currently unlicensed.
Provincial lending rules may affect loan limits, borrowing costs, cancellation rights and repayment arrangements.
How Fast Does Credit Club Approve and Fund Loans?
Credit Club promotes a fast online application process.
According to its FAQ, applicants may receive a decision within approximately one hour after submitting electronic banking verification during business hours.
Applications submitted on weekends or holidays may be processed automatically or reviewed on the next business day.
The company also advertises same-business-day funding in some circumstances.
Actual timing depends on successful verification, approval, completion of the loan agreement and electronic payment processing.
Borrowers should not rely on a guaranteed approval or transfer time when arranging an urgent payment.
For a broader comparison, read our online loans in Canada guide.
Is Credit Club Legitimate in Canada?
Credit Club is an established Canadian short-term lending business that identifies its corporate operator, publishes provincial licensing information and provides detailed borrowing-cost disclosures.
The company says it has operated since 2012.
Its official website identifies payday-lending licences in Ontario, British Columbia and Nova Scotia, although applicants should independently confirm that the relevant licence remains active.
Credit Club also has an identifiable business presence in Ottawa and a substantial history of independent customer reviews.
These factors support that Credit Club is an operating lending business. They do not eliminate the financial risks associated with payday loans.
Credit Club Better Business Bureau Rating
In November 2026, the Better Business Bureau listed Credit Club as an accredited business with an A+ rating.
Its profile states that Credit Club became BBB accredited in March 2026.
BBB accreditation and ratings are separate from government licensing and do not guarantee loan affordability, approval or customer satisfaction.
Credit Club Reviews and Customer Experiences
Independent customer feedback is one of Credit Club’s more notable strengths compared with some other online payday lenders.
Credit Club Trustpilot Reviews
In November 2026, Trustpilot displayed a rating of approximately 4.8 out of 5 stars from more than 3,700 customer reviews.
Many reviewers describe positive experiences involving:
- Quick application decisions.
- A straightforward online borrowing process.
- Helpful and professional customer service.
- Convenient electronic funding.
- Clear communication during the application process.
Not all feedback is positive. Some reviewers report:
- Loan amounts being reduced or changing between applications.
- Delays receiving funds or repayment confirmations.
- Difficulty contacting support in certain circumstances.
- Applications being declined despite previous borrowing history.
These are customer-reported experiences rather than independently verified findings.
Credit Club actively responds to customer feedback on Trustpilot. Review ratings and counts may change over time.
What Do the Reviews Tell Us?
Credit Club’s favourable review history suggests that many customers value its application speed and service.
However, a positive customer-service rating should not be confused with a low-cost borrowing product.
Even when the application process is smooth, a $14 fee for every $100 borrowed can be expensive for someone already struggling with essential expenses.
Our assessment: Credit Club has stronger independent customer feedback than many short-term lenders, but affordability and repayment capacity remain the most important considerations.
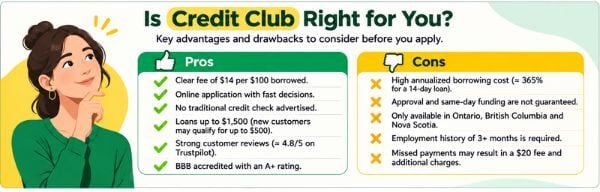
Credit Club Pros and Cons
| Potential Advantages | Potential Disadvantages |
|---|---|
| Clear advertised fee of $14 per $100 borrowed. | High annualized borrowing cost. |
| Online application and electronic funding. | Approval and same-day funding are not guaranteed. |
| No traditional credit check advertised. | Employment and banking verification are required. |
| Loans advertised up to $1,500. | New customers may qualify for only up to $500. |
| Strong independent Trustpilot feedback. | Customer reviews still report occasional delays and application difficulties. |
| BBB accreditation and A+ rating at time of review. | BBB ratings do not determine loan affordability. |
| Published provincial lending information. | Only three provinces are advertised as served. |
| No automatic payday-loan renewals advertised. | Missed payments may trigger additional charges and collection activity. |
Credit Club vs. Traditional Personal Loans
Although Credit Club uses personal-loan terminology on some of its website pages, its short-term borrowing structure differs significantly from a conventional instalment loan.
| Feature | Credit Club Payday Loan | Conventional Personal Loan |
|---|---|---|
| Borrowing amount | Generally small amounts, up to $1,500 advertised | May offer larger amounts, depending on lender |
| Cost structure | $14 per $100 borrowed | Interest rate and possible lender fees |
| Repayment | Typically linked to the next payday | Usually scheduled instalments over months or years |
| Credit assessment | No traditional credit check advertised | Depends on lender and product |
| Best suited to | Small, temporary cash shortfalls where repayment is affordable | Larger expenses or borrowing requiring longer repayment terms |
| Main risk | High short-term cost and repayment pressure | Interest accumulation and longer-term debt obligations |
A conventional personal loan is not automatically cheaper in every circumstance. Compare the total borrowing cost, all fees and repayment schedule before deciding.
Potentially Lower-Cost Alternatives to Credit Club
If you are considering a payday loan, it is worth checking whether another option can cover the expense at a lower overall cost.
1. A Credit Union or Bank Personal Loan
Depending on your credit and income, a financial institution may offer an instalment loan with a longer repayment term and a lower annualized cost.
However, some providers have minimum borrowing amounts that are higher than a typical payday loan.
2. An Existing Line of Credit
If you already have access to a line of credit, borrowing a small amount for a short period may be less expensive than paying a fixed payday-loan fee.
Interest and other charges still apply. Explore our line of credit guide.
3. An Employer Pay Advance
Some employers allow employees to access part of their earned wages before payday. Depending on the employer, this may involve a lower fee or no borrowing charge.
4. A Payment Arrangement
If you need money for rent, utilities or another bill, ask the provider whether a short payment extension or instalment arrangement is available.
This may help avoid an additional debt obligation.
5. Compare Loan Providers
If borrowing is necessary, compare providers and review their eligibility requirements, fees and repayment terms.
Explore the FatCat Loans Canadian lender network for more information about participating lending options.
FatCat Loans is a loan-matching service rather than a direct lender. Submitting an application does not guarantee a match, approval or a lower borrowing cost.
Who Should Consider Credit Club?
Credit Club May Be Worth Comparing If:
- You live in Ontario, British Columbia or Nova Scotia.
- You have steady employment and an active bank account.
- You need a relatively small amount for a temporary expense.
- You understand the $14-per-$100 borrowing fee.
- You can repay the full amount without immediately needing another loan.
Credit Club May Be Less Suitable If:
- You need more than $1,500.
- You live outside the provinces Credit Club serves.
- You do not meet the employment-history requirements.
- You need several months or years to repay.
- You are already struggling to cover basic living costs.
- You cannot comfortably repay the full loan on the agreed date.
Borrowing repeatedly to cover regular expenses can make future cash-flow problems more difficult to manage. If debt repayments are becoming unmanageable, consider speaking with a reputable non-profit credit counsellor.
Frequently Asked Questions About Credit Club Canada
Is Credit Club a legitimate lender in Canada?
Credit Club is an established Canadian short-term lender that publishes provincial licensing information and borrowing-cost disclosures. It also has BBB accreditation and a substantial customer review history. Borrowers should verify current licensing with the appropriate provincial regulator before applying.
How much does Credit Club charge for a payday loan?
Credit Club advertises a borrowing fee of $14 for every $100 borrowed. For example, a $300 loan would carry a $42 fee, bringing the total repayment to $342. Additional charges may apply if a payment is missed, subject to provincial rules.
Does Credit Club perform a credit check?
Credit Club advertises no traditional credit check. However, applicants must meet eligibility requirements and provide employment and banking information for assessment. Approval is not guaranteed.
How quickly can Credit Club approve a loan?
Credit Club states that applicants may receive a decision within approximately one hour of submitting electronic banking verification during business hours. Funding may be available the same business day, but timing is not guaranteed.
How much can first-time customers borrow from Credit Club?
Credit Club’s official FAQ states that new customers may qualify for up to $500, although the company advertises loan amounts of up to $1,500 overall. The amount offered depends on eligibility and affordability.
Which provinces does Credit Club serve?
Credit Club advertises payday loans in Ontario, British Columbia and Nova Scotia. Applicants should verify current product availability and provincial licensing before borrowing.
Final Verdict: Is Credit Club Worth Considering in 2026?
Credit Club stands out among Canadian short-term lenders for its clearly advertised borrowing fee, established operating history and strong independent customer feedback.
Its online application, no-traditional-credit-check advertising and electronic funding may appeal to eligible borrowers who need a small amount before payday.
However, the cost remains significant. A $500 loan carries a $70 borrowing fee, and a typical 14-day arrangement produces a high annualized borrowing cost.
The short repayment period can also create financial pressure, particularly for borrowers whose next paycheque is already committed to rent, groceries and other essential expenses.
Our assessment: Credit Club may be worth comparing if you meet its eligibility requirements, understand the total borrowing cost and can repay comfortably on schedule. Its favourable customer reviews are a positive consideration, but they do not make payday borrowing inexpensive.
Before applying, compare alternative financing options, confirm current provincial licensing and review the full agreement carefully.
For more information about your protections, read our Canadian borrower rights guide.
Sources
- Credit Club – Official Website
- Credit Club – Pricing and Borrowing Fees
- Credit Club – Rates, Terms and Provincial Disclosures
- Credit Club – Frequently Asked Questions
- Credit Club – Licensing and Regulatory Compliance
- Credit Club – Published Ontario Licence Certificate
- Trustpilot – Credit Club Customer Reviews
- Better Business Bureau – Credit Club Business Profile
- Financial Consumer Agency of Canada – Payday Loans
Editorial note: This review is based on publicly available information checked in November 2026. FatCat Loans has not independently completed a Credit Club application or received a personalized loan offer. Product terms, fees, customer ratings and provincial licensing status may change.
Disclaimer: This article is for general information only and does not constitute financial or legal advice. FatCat Loans is a loan-matching service, not Credit Club or a direct lender. Loan approval, costs and funding depend on the provider, applicant and applicable provincial rules. Always review the current loan agreement before borrowing.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.