Bree Review Canada (2026): Is It Worth Using?
August 07, 2026
Should You Consider Bree?
Last Updated: August 2026
Unexpected expenses can happen to anyone. Whether it’s a vehicle repair, grocery bill, utility payment or another emergency expense, waiting until payday isn’t always an option.
Bree is a Canadian financial app that offers eligible users access to a cash advance of up to $750. Unlike a traditional payday lender, Bree does not charge mandatory interest or mandatory borrowing fees on its standard cash advance. Instead, it offers optional tips, optional membership features and optional express funding for borrowers who need money more quickly. Learn more about Bree here.
That makes Bree quite different from many short-term lenders operating in Canada. However, that doesn’t automatically mean it’s the right solution for everyone.
In this Bree Review Canada, we’ll explain:
- How Bree works
- Who may qualify
- How much you can borrow
- Potential advantages and disadvantages
- Whether Bree is legitimate
- How it compares with other borrowing options
- Whether it’s a better choice than a traditional payday loan
Our goal is to help you decide whether Bree is the right borrowing option for your situation.
Table of Contents
- Bree Review: Quick Summary
- What Is Bree and How Does It Work?
- Bree at a Glance
- Bree Pros and Cons
- Who Can Apply for Bree?
- How Much Can You Borrow?
- Bree Compared With Other Borrowing Options
- Is Bree Legit?
- Should You Use Bree?
- Frequently Asked Questions
- Final Verdict
Bree Review: Quick Summary
Bottom Line: Bree offers eligible Canadians access to a cash advance of up to $750 without mandatory interest charges, mandatory borrowing fees or a traditional credit check. While it can be a useful option for genuine short-term cash-flow gaps, borrowers should still ensure they can comfortably repay the advance on their next payday and compare alternative borrowing options before applying.
What Is Bree and How Does It Work?
Bree is a Canadian financial app that provides eligible users with access to a short-term cash advance rather than a conventional payday loan.
Instead of charging interest on the amount borrowed, Bree’s standard advance is designed to help users bridge the gap between paydays without mandatory borrowing costs. Users can optionally leave a tip or choose express funding if they need the money more quickly, although these options are not required to receive a standard advance.
The application process is completed entirely online through the Bree website or mobile app.
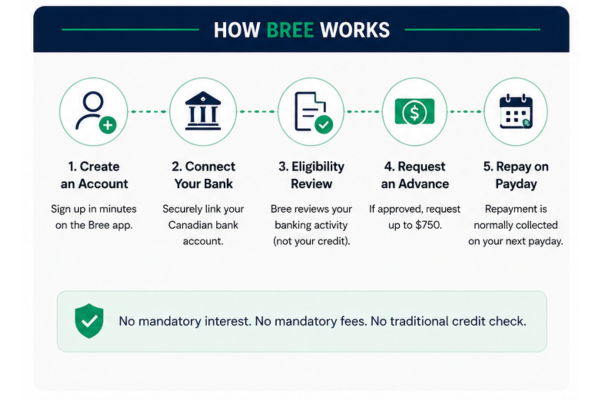
Eligible applicants typically:
- Create a Bree account
- Securely connect their Canadian bank account
- Receive an eligibility review
- Request a cash advance if approved
- Repay the advance from their next payday or other agreed repayment date
Unlike many payday lenders, Bree states that it does not perform a traditional credit check when assessing applications. Instead, it reviews factors such as banking activity, income patterns and account history to determine eligibility.
Because Bree is a cash advance product rather than a traditional instalment loan, it’s important to understand how it compares with other borrowing options. In many situations, a personal loan or line of credit may be better for larger expenses or longer repayment periods.
Bree at a Glance
| Feature | Details |
|---|---|
| Product type | Cash advance / line of credit |
| Maximum advance | Up to $750 for eligible users |
| Application | Completed online or through the Bree app |
| Interest | No mandatory interest charges |
| Mandatory fees | None for standard funding |
| Express funding | Available for an optional fee |
| Credit check | Bree states that it does not perform a traditional credit check |
| Repayment | Normally collected on your next payday or agreed repayment date |
| Best suited to | Short-term cash-flow gaps and emergency expenses |
| Lower-cost alternatives | Personal loans, lines of credit or overdraft protection where available |
Quick Facts About Bree
- Maximum cash advance: Up to $750
- Traditional credit check: No
- Mandatory interest: None
- Mandatory borrowing fees: None
- Repayment: Usually on your next payday
- Best for: Small, short-term emergency expenses
- Our rating: ★★★★☆ (4.6/5)
Bree Pros and Cons at a Glance
| Potential Benefits | Potential Drawbacks |
|---|---|
| Up to $750 available for eligible users | Not everyone will qualify |
| No mandatory interest charges | Advance limits may initially be lower |
| No traditional credit check | Express funding costs extra |
| Simple online application process | Repayment is generally expected on your next payday |
| May help avoid expensive payday loans | Should not be relied on for ongoing financial shortfalls |
Bree can be an attractive option for borrowers who need a relatively small amount of money for a genuine emergency and expect to repay it quickly. However, it should not be viewed as a long-term solution for recurring financial difficulties.
If you regularly need to borrow money between paydays, it may be worth comparing products such as a personal loan or line of credit, or seeking help from a non-profit organization offering credit counselling in Canada before relying on repeated short-term borrowing.
Who Can Apply for Bree?
Bree is designed for Canadians who need access to a relatively small amount of money before payday. While eligibility requirements may change over time, applicants generally need to meet several basic criteria before they can access a cash advance.
According to Bree, you’ll typically need to:
- Be at least 18 years old
- Live in Canada
- Have an active Canadian bank account
- Have a Visa or Mastercard debit card linked to your bank account
- Receive regular income into the connected account
Unlike many traditional lenders, Bree says it does not rely on a conventional credit check when assessing applications. Instead, it reviews factors such as your income patterns, banking activity and account history to determine eligibility and your available borrowing limit.
Because approval is based on your overall financial profile rather than simply your credit score, not every applicant will qualify. Some users may also receive a lower initial borrowing limit that increases over time following successful repayments.
How Much Can You Borrow?
Bree currently offers eligible users access to a cash advance of up to $750. However, the amount available depends on your individual financial profile and the information Bree reviews during the application process.
New users may initially qualify for a smaller advance. If repayments are made successfully and your account remains in good standing, Bree may increase your available limit over time.
Repayment is usually collected automatically from your linked bank account on your next payday or another agreed repayment date. You can also repay your cash advance early without penalty.
Standard cash advances don’t include mandatory interest or mandatory borrowing fees. However, optional costs may apply if you choose Express Delivery or other paid services. Always review the total cost before accepting an advance.
If you need more than $750 or require a longer repayment period, a personal loan or personal line of credit may provide greater flexibility.
When Bree May Not Be the Right Choice
Bree is intended to help cover temporary cash-flow gaps rather than ongoing financial needs. Although it may be useful for an unexpected expense, it isn’t designed to replace longer-term borrowing or solve recurring money problems.
You should avoid relying on Bree if you need money to:
- Pay rent every month
- Cover ongoing grocery bills
- Repay existing loans
- Consolidate debt
- Fund large purchases
If you regularly need to borrow before payday, comparing a personal loan, line of credit or speaking with a non-profit credit counselling agency may provide a more sustainable solution.
Bree Compared With Other Borrowing Options
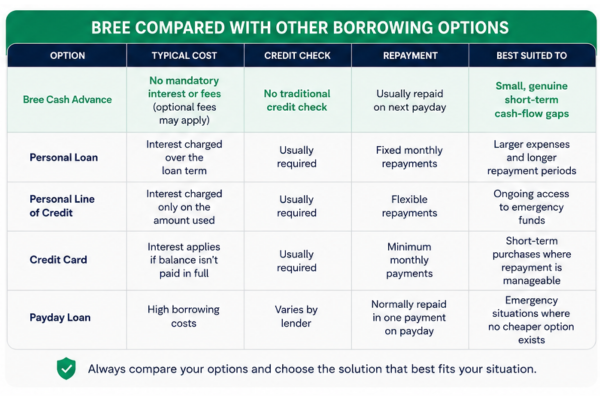
The most important comparison isn’t simply between different cash advance apps. It’s whether a cash advance is the most suitable borrowing option for your financial situation.
| Option | Typical Cost | Credit Check | Repayment | Best Suited To |
|---|---|---|---|---|
| Bree Cash Advance | No mandatory interest or mandatory fees (optional fees may apply) | No traditional credit check | Normally repaid on your next payday | Small, genuine short-term cash-flow gaps |
| Personal Loan | Interest charged over the loan term | Usually required | Fixed monthly repayments | Larger expenses and longer repayment periods |
| Personal Line of Credit | Interest charged only on the amount used | Usually required | Flexible repayments | Ongoing access to emergency funds |
| Credit Card | Interest applies if the balance isn’t paid in full | Usually required | Minimum monthly payments | Short-term purchases where repayment is manageable |
| Payday Loan | High borrowing costs | Varies by lender | Normally repaid in one payment on payday | Emergency situations where no cheaper option exists |
For many borrowers, Bree may be a more affordable option than a traditional payday loan because it doesn’t charge mandatory interest or mandatory borrowing fees on its standard advance. However, it’s still intended as a short-term solution rather than ongoing financial support.
Bree may appeal to borrowers who want a short-term cash advance without mandatory interest charges or a traditional credit check. However, if you need a larger amount, more flexible repayments or ongoing access to credit, a personal loan or line of credit may be a better fit.
If you’re trying to decide between different credit products, our guides on Personal Loan or Line of Credit? and Personal Line of Credit vs Credit Card explain the differences in more detail.
You can also compare other reputable lenders in our guide to the Best Online Lenders in Canada before making a borrowing decision.
The Financial Consumer Agency of Canada also recommends comparing borrowing costs, repayment obligations and alternatives before taking on new debt. Learn more from the FCAC.
Is Bree Legit?
Yes. Based on our review, Bree appears to be a legitimate Canadian financial technology company offering short-term cash advances to eligible users.
Bree operates differently from a traditional lender. Rather than offering long-term loans, it provides eligible users with access to short-term cash advances through its app. As with any financial product, it’s important to review the latest terms, repayment conditions and optional fees before accepting an advance.
Unlike many payday lenders, Bree promotes a different borrowing model. It states that its standard advances have no mandatory interest charges, no mandatory borrowing fees and no traditional credit check. Instead, the company generates revenue through optional tips, optional membership features and optional express funding services.
That said, borrowers should always read the current terms and conditions before accepting any financial product. Features, eligibility requirements, repayment terms and optional fees can change over time.
It’s also worth remembering that “legitimate” doesn’t automatically mean “appropriate.” Even relatively low-cost borrowing should only be used for genuine short-term financial needs where repayment is affordable.
Should You Use Bree?
Bree could be the right option if you:
- Need a relatively small amount before payday
- Can comfortably repay the advance from your next income
- Want to avoid traditional payday-loan fees
- Don’t qualify for lower-cost conventional credit
However, Bree may not be the right solution if:
- You regularly run out of money before payday
- You need more than $750
- You require several months to repay the money
- You’re borrowing to cover ongoing living expenses
Repeated reliance on any short-term borrowing product can indicate a wider budgeting issue. If you’re finding it difficult to keep up with debt repayments, speaking with a non-profit organization that provides credit counselling in Canada may help you explore longer-term solutions before your financial situation becomes more difficult.
For borrowers who need larger amounts or more flexible repayment options, comparing a personal loan or line of credit may be a more sustainable long-term choice.
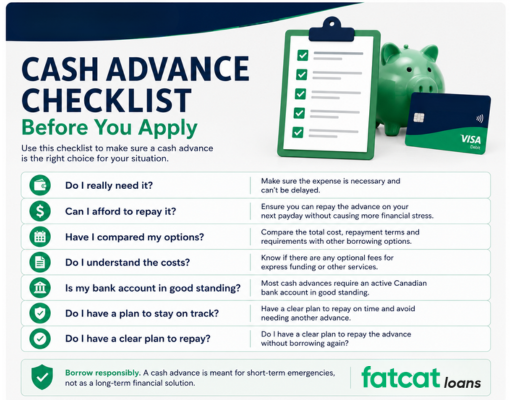
Checklist Before Using Bree
Before requesting a cash advance through Bree, ask yourself the following questions:
- ✓ Is this a genuine emergency or unexpected expense?
- ✓ Can I comfortably repay the advance on my next payday?
- ✓ Have I compared other borrowing options?
- ✓ Do I understand any optional fees or Express Delivery charges?
- ✓ Have I read Bree’s latest terms and conditions?
- ✓ Do I have a clear plan to repay the advance without borrowing again?
If you answer “no” to any of these questions, it may be worth exploring other borrowing options before proceeding.
Frequently Asked Questions About Bree
Is Bree legit in Canada?
Yes. Bree is a Canadian app that lets eligible users access a cash advance instead of a traditional payday loan. Always review the latest terms and conditions before applying.
How much can I borrow from Bree?
Bree currently offers eligible users access to cash advances of up to $750. Your available limit depends on your financial profile and Bree’s assessment.
Does Bree charge interest?
Bree states that it does not charge mandatory interest on its standard cash advance. Optional costs may apply if you choose services such as Express Delivery or optional membership features.
Does Bree perform a credit check?
Bree says it does not perform a traditional credit check when assessing applications. Instead, it reviews information such as your income patterns and banking activity to determine eligibility.
How quickly can I receive my money?
Funding times depend on the option you choose, your financial institution and successful verification of your application. Express Delivery may be available for an additional fee.
Can I use Bree if I have bad credit?
Possibly. Because Bree does not rely on a traditional credit check, some applicants with weaker credit histories may still qualify. Approval is never guaranteed and depends on Bree’s review criteria.
Is Bree better than a payday loan?
For many borrowers, Bree may be a lower-cost alternative because it doesn’t charge mandatory interest or mandatory borrowing fees on its standard cash advance. However, it is still intended as short-term borrowing and should only be used when repayment is affordable.
Should I use Bree for ongoing expenses?
No. Cash advances are designed for temporary financial emergencies rather than recurring bills or long-term budget shortfalls. If you’re borrowing regularly between paydays, a longer-term solution may be more appropriate.
Final Verdict
Bree offers a different approach to short-term borrowing than many traditional payday lenders operating in Canada. By providing eligible users with access to cash advances of up to $750 without mandatory interest charges or mandatory borrowing fees, it may be a useful option for people facing a genuine temporary cash-flow shortage.
It isn’t designed as a long-term borrowing solution. Even when borrowing costs are lower than those associated with many payday loans, you’ll still need to repay the advance from your next income, making affordability an important consideration.
Only borrow what you genuinely need and avoid taking on new debt if you’re unsure you’ll be able to repay it on time.
If you qualify for more traditional forms of borrowing, products such as a personal loan or line of credit may offer greater flexibility and higher borrowing limits.
If you’re still comparing lenders, our guide to the Best Online Lenders in Canada provides an overview of reputable lending options to help you choose the solution that best matches your financial needs.
Overall Rating: ★★★★☆ (4.6/5)
- Application Process: ★★★★★
- Transparency: ★★★★★
- Cost: ★★★★☆
- Repayment Flexibility: ★★★☆☆
- Overall Value: ★★★★☆
Why Trust FatCat Loans?
Our lender reviews are written to help Canadians understand how different borrowing products work. We review publicly available information, lender terms and consumer resources to provide balanced, educational content. Our reviews are not sponsored by the lenders we write about, and we aim to explain both the advantages and potential drawbacks so you can make an informed decision.
Disclaimer
This review is provided for informational purposes only and should not be considered financial advice. Loan products, eligibility requirements, fees and borrowing limits may change over time. Always review the latest information on the lender’s website before applying and compare multiple borrowing options before making a financial decision.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.