Personal Loan vs Line of Credit in Canada: Which Is Best?
May 03, 2024
Personal Loan vs Line of Credit: Which Should You Choose?
Last Updated: August 2026
Personal loans and lines of credit both provide access to borrowed money, but they work in very different ways. A personal loan usually provides a lump sum that you repay over an agreed term, while a line of credit lets you borrow, repay and reuse funds up to an approved limit.
The better option depends on why you’re borrowing, how much flexibility you need and whether you prefer structured repayments or ongoing access to credit.
This guide compares personal loans and lines of credit in Canada, including how interest works, repayment differences, credit-score considerations and when each option may make more sense.
Quick Answer: Personal Loan or Line of Credit?
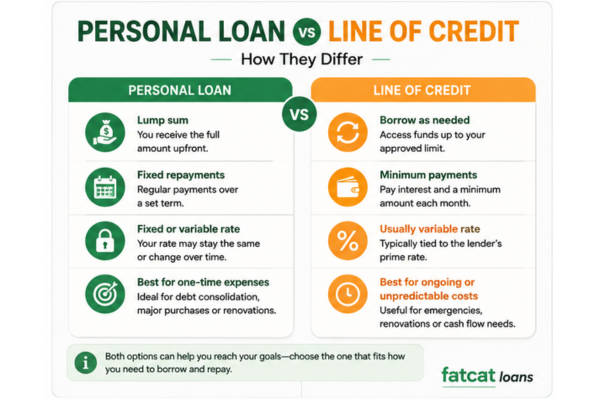
A personal loan may be better when you need a set amount for a one-time expense and want structured repayments over an agreed period. This can work well for debt consolidation, a major purchase or a planned expense.
A line of credit may be better when costs are ongoing or unpredictable and you want the flexibility to borrow, repay and reuse available credit.
The main difference is:
Personal loan = borrow once and repay on a schedule.
Line of credit = borrow as needed and reuse available credit.
Cost matters too. Personal loans may have fixed or variable rates, while lines of credit usually have variable rates. Your actual rate and terms depend on the lender and your financial profile.
Personal Loan vs Line of Credit at a Glance
| Feature | Personal Loan | Line of Credit |
|---|---|---|
| How you borrow | Lump sum | As needed |
| Credit type | Instalment credit | Revolving credit |
| Access to funds | Usually once | Ongoing up to your limit |
| Interest rate | Fixed or variable | Usually variable |
| Interest charged | On the loan balance | On the amount borrowed |
| Repayment | Scheduled instalments | Minimum payments |
| Repayment period | Set term | Usually no fixed payoff date |
| Reuse repaid funds | No | Yes |
| Best suited to | One-time expenses | Ongoing or unpredictable costs |
According to the Financial Consumer Agency of Canada (FCAC), a line of credit allows you to borrow money up to a preset limit, with interest charged on the amount you actually borrow.
How Do Personal Loans Work?
Personal loans provide a lump sum that can be used for various purposes. Lenders may consider factors such as your credit history, income and existing debts when deciding whether to approve an application and what terms to offer.
Personal loans are generally repaid through regular instalments over an agreed term. FCAC says personal loan terms commonly range from 6 to 60 months, although terms vary by lender and product. They are commonly used for purposes such as debt consolidation, home improvement projects, or unexpected expenses.
Personal loans may be secured or unsecured. A secured loan uses an asset as collateral, while an unsecured loan does not.
If you’re new to personal loans, our Personal Loans Canada guide explains how they work in more detail, including eligibility, borrowing costs and what to compare before choosing an offer.
How Does a Line of Credit Work?
A line of credit is a form of revolving credit that gives you access to funds up to an approved limit.
For example, if you have a $10,000 line of credit but only borrow $2,000, you generally pay interest on the $2,000 you’ve used rather than the full $10,000 limit.
As you repay the balance, that credit becomes available to use again. This can make a line of credit useful for ongoing or unpredictable expenses where you don’t know exactly how much you’ll need upfront.
Lines of credit can be secured or unsecured. Interest rates are usually variable, which means your borrowing cost can rise or fall over time.
FCAC also warns that some minimum payments may cover only the monthly interest. If you continually pay only the interest, you won’t reduce the original amount borrowed.
Comparing Interest Rates and Borrowing Costs
Interest rates can work differently depending on the product.
Personal loans may have fixed or variable interest rates. With a fixed rate, the rate remains the same during the agreed period, which can make repayments easier to budget for. A variable rate may change over time.
Lines of credit usually have variable rates. A lender may quote the rate in relation to its prime rate, such as prime + 3%. If the applicable rate rises, the interest charged on your outstanding balance can increase.
The Bank of Canada publishes current Canadian interest-rate data, which can help borrowers understand the wider rate environment.
With a line of credit, you generally pay interest only on the amount you’ve actually borrowed.
However, don’t compare products using the interest rate alone. Consider:
- The rate you’re actually offered
- Whether the rate is fixed or variable
- Applicable fees
- How much you’re borrowing
- How long you’ll carry the debt
- The total cost of borrowing
How Do Personal Loans and Lines of Credit Affect Your Credit?
Both personal loans and lines of credit can affect your credit profile. Applying may involve a credit check, while your payment history after approval can also affect your credit.
A personal loan is instalment credit, while a line of credit is revolving credit. With revolving credit, how much of your available credit you’re using can also be relevant.
In either case, making required payments on time and avoiding more debt than you can comfortably manage are important.
Read our guide to how personal loans affect your credit score for a more detailed explanation.
Repayment Terms and Flexibility
A personal loan usually has a defined repayment schedule. You make regular payments until the loan is repaid, giving you a clearer idea of when the debt should end.
A line of credit offers more flexibility. You can borrow, repay and reuse available funds, but there may be no fixed date by which the entire balance must be cleared.
That flexibility can be useful, but it also requires discipline. Making only the minimum payment can keep revolving debt around much longer.
If predictable budgeting is important to you, a personal loan may be easier to manage. If flexible access to funds matters more, a line of credit may be more suitable.
Pros and Cons of Personal Loans
Advantages
- Structured repayments: Regular payments and a defined loan term can make budgeting easier.
- Lump-sum funding: Useful when you know how much you need upfront.
- Fixed-rate options: A fixed rate can provide predictable borrowing costs.
- Clear payoff date: Following the repayment schedule naturally moves the debt towards being cleared.
Disadvantages
- Less flexible: If you need additional funds later, you may need to apply for more credit.
- Interest on the borrowed amount: You take the agreed loan amount upfront rather than drawing only what you need over time.
- Rates vary: Borrowers with weaker credit may receive higher rates.
- Collateral risk: With a secured loan, the asset used as security may be at risk if you don’t repay as agreed.
Pros and Cons of Lines of Credit
Advantages
- Flexible access: Borrow money as you need it.
- Reusable credit: Repaid funds generally become available again.
- Interest on funds used: You generally pay interest only on what you’ve borrowed.
- Useful for unpredictable costs: You don’t need to know the exact expense upfront.
Disadvantages
- Variable rates: Borrowing costs can increase if rates rise.
- No automatic payoff date: The balance can remain outstanding for a long time.
- Overspending risk: Easy access to available credit can encourage additional borrowing.
- Minimum payments: Paying only the minimum may reduce the principal very slowly — or, in some cases, not at all.
Ready to explore your borrowing options? Compare loan options available through FatCat Loans’ lending partners.
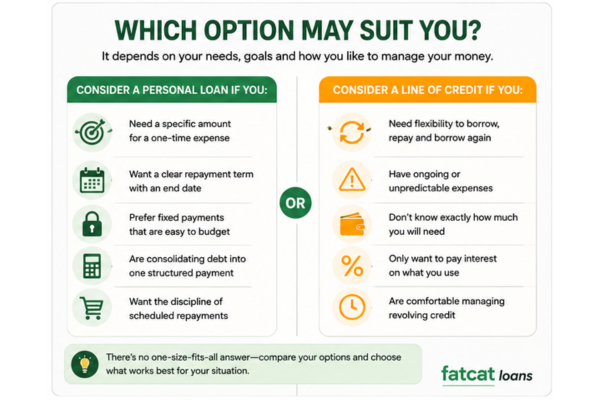
Personal Loan or Line of Credit: Which Is Right for You?
Your borrowing purpose can help point you towards the more suitable option.
| If You… | Consider |
|---|---|
| Need a specific amount once | Personal loan |
| Want a defined repayment period | Personal loan |
| Prefer predictable payments | Fixed-rate personal loan |
| Want structured debt consolidation | Personal loan |
| Need money at different times | Line of credit |
| Don’t know exactly how much you’ll need | Line of credit |
| Want to reuse available credit | Line of credit |
| Can manage revolving debt carefully | Line of credit |
| Want the lowest overall borrowing cost | Compare actual offers |
A useful question is:
“Is this a one-time expense or an ongoing need?”
A personal loan is generally better suited to a known one-time expense. A line of credit may be better suited to costs that arise over time.
However, the product type shouldn’t be your only consideration. Compare the actual interest rate, fees, repayment requirements and total borrowing cost you’re offered.
Common Scenarios
Debt consolidation: A personal loan may be useful when you want to combine several debts into one structured repayment. You can also compare debt consolidation loan options if consolidating existing debts is your main reason for borrowing.
Emergency expenses: A line of credit may suit unpredictable costs, while a personal loan may suit an emergency where you already know how much you need.
Home renovations: A personal loan may work for a fixed renovation budget, while a line of credit can provide flexibility when costs arise at different stages.

Questions to Ask Before You Borrow
Before choosing a personal loan or line of credit, ask:
- How much do I actually need?
- Can I comfortably afford the repayments?
- Is the interest rate fixed or variable?
- What fees apply?
- What happens if interest rates rise?
- How long could I carry this debt?
- What happens if I miss a payment?
- Is the borrowing secured against an asset?
- What is the total expected cost?
If you’re unsure how much debt your budget can comfortably support, our debt-to-income ratio Canada guide explains how income and existing debts can affect borrowing decisions.
Before borrowing, estimate how different loan amounts, rates and terms could affect your repayments.

Frequently Asked Questions
What Determines Eligibility for Personal Loans vs. Lines of Credit?
Lenders may consider your credit history, income, existing debts and overall ability to repay when assessing either product. Eligibility requirements and approval criteria vary between lenders.
Can I Have Both a Personal Loan and a Line of Credit?
Yes. You can have both, subject to lender approval. However, consider your existing debts, income and ability to manage both accounts before taking on additional credit.
How Do Interest Rates Compare Between Personal Loans and Lines of Credit?
Personal loans may have fixed or variable interest rates, while lines of credit usually have variable rates. A line of credit rate may be linked to the lender’s prime rate, so your borrowing cost can change over time.
Which is easier to qualify for in Canada: a personal loan or a line of credit?
There is no universal answer. Approval depends on the lender’s criteria and your financial profile. Lenders may consider factors such as your credit history, income and existing debts when assessing either type of credit.
Is a personal loan better than a line of credit?
Neither is always better. A personal loan may suit a one-time expense when you want structured repayments, while a line of credit may suit ongoing or unpredictable expenses where flexible access to money is more important.
Is a line of credit cheaper than a personal loan?
Not necessarily. Lines of credit may offer competitive rates, but the actual cost depends on the rate you’re offered, how much you borrow and how long you carry the balance. Compare the total borrowing cost rather than the advertised rate alone.
Can I use a line of credit for debt consolidation?
Yes. A line of credit may be used to consolidate other debts. However, because the credit remains available after you repay it, disciplined borrowing is important to avoid building the balances back up.
Final Verdict: Personal Loan or Line of Credit?
A personal loan may be the better choice when you know how much you need and want a structured repayment plan with a defined end date.
A line of credit may be the better choice when expenses are ongoing or unpredictable and you value the ability to borrow, repay and reuse available credit.
The biggest difference isn’t simply the interest rate. It’s how the debt behaves after you borrow.
A personal loan naturally moves towards a payoff date as you make scheduled payments. A line of credit offers more flexibility, but that flexibility requires careful management to prevent the balance from becoming long-term debt.
Before choosing either, compare the interest rate, fees, repayment requirements and total borrowing cost — and make sure the payments comfortably fit your budget.
Disclosure: This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.

The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in Canada. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.